Financial & Forex Market Recap: Nov. 18, 2026
On Nov. 18, 2026, Fed hike talk lifted the dollar to a 19-month high, gold and Bitcoin fell more than 3%, and a U.S. crude build sank oil about 3%.
A louder hawkish chorus from the Federal Reserve ran the show on Wednesday. Fed Governor Christopher Waller floated a half-point hike, the October meeting minutes showed almost all officials expect more increases, and the U.S. dollar touched a fresh 19-month high. Gold and Bitcoin each lost more than 3%, while a surprise build in U.S. crude stocks sank oil about 3% and likely helped pull the 10-year Treasury yield lower.
In short: On Wednesday, Nov. 18, 2026, Fed hike bets lifted the Dollar Index 0.2% to near 103.78 and knocked gold 3.2% lower to near $3,725, its weakest level in more than a year. WTI crude fell 3.0% to near $83.21 after a U.S. inventory build, and Bitcoin dropped 3.3% to near $62,534.
Wednesday’s Market Scoreboard: Gold and Bitcoin Sink as the Dollar Climbs
| Asset | Close (approx.) | Day change | Driver |
|---|---|---|---|
| S&P 500 | 7,322 | -0.86% | Nvidia pop faded, hawkish Fed |
| U.S. 10-year yield | 5.06% | -0.88% (about -4.5 bp) | Oil slide outweighed Fed talk |
| U.S. Dollar Index | 103.78 | +0.21% | Waller, minutes lifted hike bets |
| WTI crude oil | $83.21 | -2.98% | Surprise U.S. crude build |
| Gold | $3,725 | -3.22% | Hike bets, firm dollar |
| Bitcoin | $62,534 | -3.28% | ETF outflows, long liquidations |
| USD/JPY | 159.31 | -0.06% | Cheaper oil, Ueda hike talk |
| EUR/USD | 1.0978 | -0.22% | Broad dollar strength |
| GBP/USD | 1.3150 | -0.44% | Steady core CPI, softer services |
| USD/CHF | 0.8433 | +0.29% | Dollar bid on Fed bets |
| AUD/USD | 0.6717 | -0.30% | Wage beat faded, risk-off |
| NZD/USD | 0.5493 | +0.03% | Flat, beat commodity peers |
| USD/CAD | 1.4326 | +0.23% | Oil slump hit the loonie |
Approximate levels, 6:00 pm ET Tuesday to 4:00 pm ET Wednesday. Drivers are likely factors, not confirmed causes.
Forex News Headlines & Data: U.K. CPI, Australian Wages, Waller and the Fed Minutes
- Japan Balance of Trade for October 2026: -¥476.5 billion (-¥956.0 billion forecast; -¥556.5 billion previous)Above forecast
- Exports: 20.5% y/y, a record high (20.0% forecast; 16.5% previous)Above forecast
- Imports: 21.6% y/y (25.8% forecast; 18.5% previous)Below forecast
-
Australia Wage Price Index for Q3 2026: 1.1% q/q (0.9% forecast; 0.7% previous)Above forecast
- Annual wage growth: 3.5% y/y (3.3% forecast; 3.2% previous)Above forecast
- Bank of Japan Governor Kazuo Ueda said the BOJ should keep raising rates because financial conditions remain accommodative
- Iran said it attacked U.S. drone and missile sites in Kuwait after a U.S. strike on Qeshm Island in the Strait of Hormuz
- U.K. CPI for October 2026: 3.6% y/y (3.6% forecast; 3.5% previous)In line
- Core CPI: 2.8% y/y (2.8% forecast; 2.8% previous)In line
- Services CPI: 3.7% y/y (3.8% forecast; 3.7% previous)Below forecast
Why it mattered: Steady core and services inflation likely eased pressure on the Bank of England to hike in December, and the pound slid to a one-month low against the dollar.
- Euro area final CPI for October 2026: 4.0% y/y (4.0% forecast; 3.8% previous)In line
- Core CPI: 2.6% y/y, revised up from the 2.5% flash estimate
- Fed Governor Christopher Waller told CNBC a half-point hike is probably needed in December unless the Fed signals a faster pace of hikes in 2027
- Building Permits: 1.295M (1.377M forecast; 1.398M previous)Below forecast
- Bank of England Governor Andrew Bailey said a longer Middle East conflict makes persistent inflation and higher rates more likely
- U.S. Pending Home Sales for October 2026: -4.7% m/m (-2.0% forecast; -7.2% previous)Below forecast
- EIA Crude Oil Stocks Change for the week to Nov. 13: +3.38M barrels (-0.48M forecast; +4.66M previous)Forecasts differ
- Gasoline Stocks Change: +5.19M barrels (+1.70M forecast; +1.80M previous)Above forecast
Why it mattered: A crude build when traders expected little change added to worries about a supply surplus, and WTI fell about 3% on the day.
- Fed Governor Michael Barr said it will likely be appropriate to raise rates further if the economy evolves as he expects
- The U.S. Treasury sold $16 billion of 20-year bonds at 5.459% with a 2.63 bid-to-cover ratio
- FOMC Meeting Minutes for October 2026: almost all officials judged that further rate hikes would likely be appropriate, and a couple said a bigger-than-usual hike could be considered in December if inflation data disappoint
Broad Market Price Action: Hawkish Fed Hits Gold and Bitcoin as Oil Slides
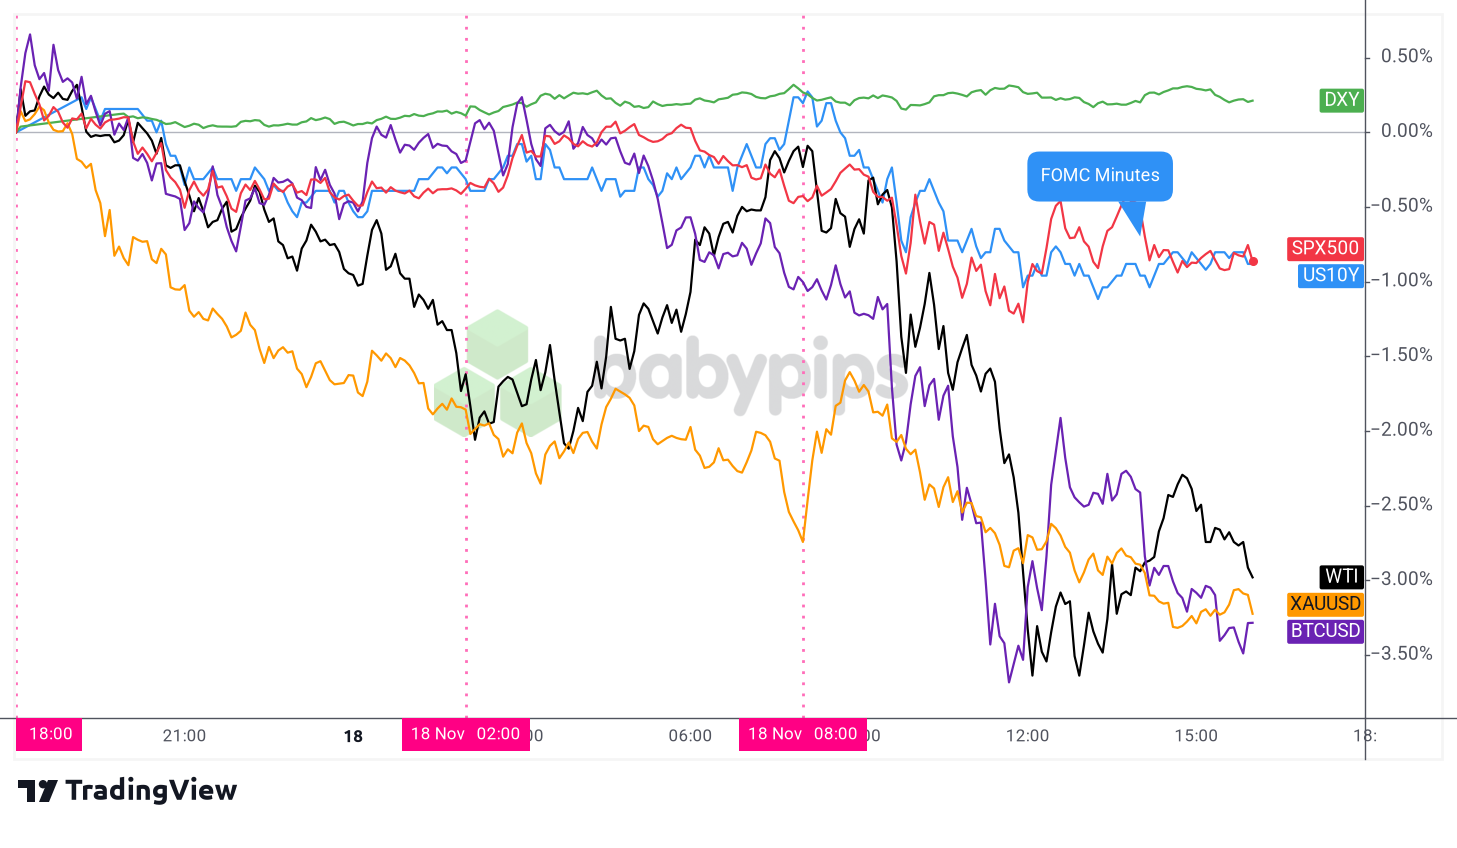
The Fed did most of the talking. Waller told CNBC before the U.S. open that inflation is “headed in the wrong direction” and that the Fed may need a half-point hike in December. Barr also said more hikes look likely, and the 2:00 pm ET minutes showed almost all officials expected further increases. Markets still lean toward a smaller step, though. CME FedWatch showed a 94.7% chance of a quarter-point December hike as of Wednesday’s close, Reuters reported.
Gold and Bitcoin took the hardest hits. Gold slid about 3.2% to near $3,725 after it fell to its lowest level in more than a year. Higher expected U.S. rates raise the cost of holding a metal that pays no interest, and the dollar’s fresh 19-month high probably added pressure. Bitcoin lost about 3.3% to near $62,534. Ongoing spot ETF outflows, long liquidations and a cut to Citi’s 12-month Bitcoin target likely kept buyers on the sidelines.
Oil dropped on fresh supply worries. The EIA said U.S. crude stocks rose by about 3.4 million barrels last week when traders expected little change, and gasoline stocks jumped about 5.2 million barrels. WTI fell about 3.0% to near $83.21, with much of the drop coming in the 90 minutes after the 10:30 am ET report. Iran’s reported strikes on U.S. sites in Kuwait kept some supply risk alive but didn’t stop the selling.
Cheaper oil probably eased inflation worries further out the curve. The 10-year yield fell about 4.5 basis points to near 5.06%, while the two-year yield edged higher on the hawkish Fed talk. That split suggests traders see more near-term hikes but less long-run inflation risk.
The S&P 500 couldn’t hold its overnight Nvidia bounce and ended about 0.9% below Tuesday evening’s level, near 7,322. Nvidia beat forecasts and guided revenue above estimates, but its shares fell 2.4% amid uncertainty after Jensen Huang’s sudden exit as CEO. The cash index closed down 0.3% at 7,321, the Dow lost 1.1% and the Nasdaq added 0.3% as traders waited for Anthropic’s IPO pricing after the close.
Market concept of the dayWhy Do Fed Rate Hike Bets Hit Gold So Hard?
Gold doesn’t pay interest. When traders expect the Fed to keep hiking, cash and short-term Treasuries pay more, so holding gold means giving up more income. A stronger dollar adds a second hit, since gold is priced in dollars and gets pricier for buyers who use other currencies. On Wednesday both forces lined up after Waller’s remarks, which may explain why gold fell harder than stocks. You can dig deeper in What Makes Gold’s Price Move? in the School of Pipsology.
FX Market Behavior: U.S. Dollar vs. Majors
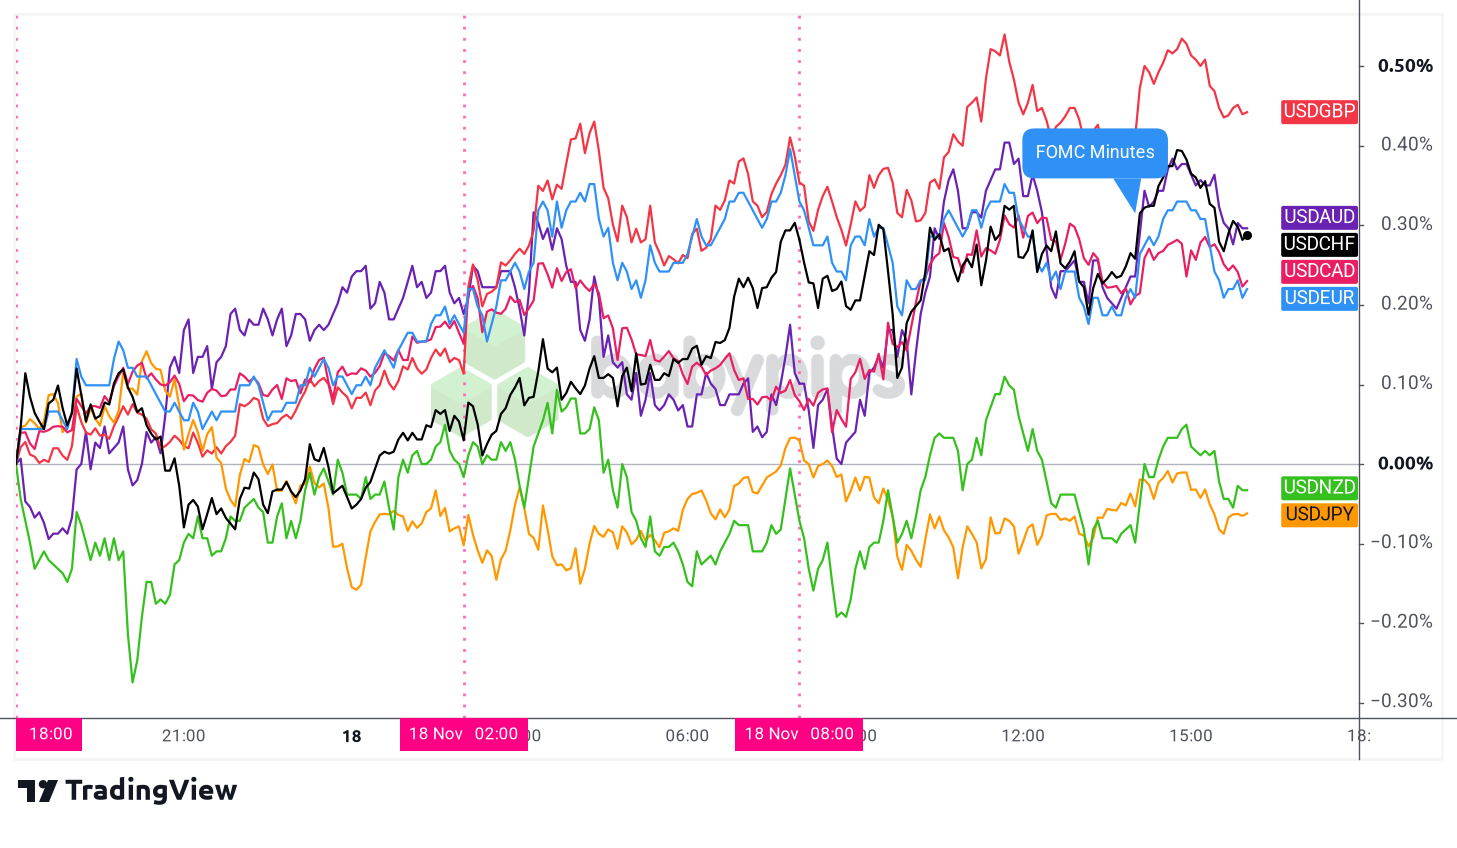
The U.S. dollar beat most majors, and the Dollar Index rose about 0.2% to near 103.78 after touching its highest level since April 2025. The Japanese yen was the strongest major, edging up about 0.1% against the dollar, and the New Zealand dollar finished roughly flat. The British pound was the weakest, down about 0.4% to near 1.3150. The Australian dollar, Swiss franc, Canadian dollar and euro each lost 0.2% to 0.3%.
Waller’s half-point talk on CNBC likely sparked the dollar’s run, and the Dollar Index hit its session high near 103.89 around 7:45 am ET. The minutes seemed to add little that markets hadn’t already priced, and the dollar eased into the close as long-term yields slipped.
The pound probably suffered from a softer-than-hoped U.K. inflation mix. Headline CPI rose to 3.6% as expected, but core inflation held at 2.8% and services inflation stayed at 3.7%. Money markets trimmed odds of a December Bank of England hike to about 80% from about 90% before the release, even as Bailey warned that a longer energy shock could keep inflation sticky. The euro briefly hit its lowest level since April 2025, and confirmed 4.0% euro area inflation didn’t change the ECB picture much.
The yen held up best. Ueda’s call for more BOJ hikes likely helped, and cheaper oil may have eased pressure on Japan’s energy import bill. Worries about intervention near 160 per dollar also probably kept a lid on USD/JPY. The Canadian dollar slipped as oil slumped. The Aussie got little lift from the fastest quarterly wage growth since late 2023, likely because the selloff in metals and crypto weighed on commodity currencies ahead of Thursday’s jobs report.
On Premium this weekThis week’s Fundies Cheat Sheet flagged the Fed minutes and Nvidia’s report as the week’s big tests for the dollar, gold and stocks, and our U.K. CPI Event Guide previewed Wednesday’s inflation report. Both are part of Babypips Premium.
Upcoming Potential Catalysts on the Economic Calendar: Australian Jobs, U.S. Claims and Japan CPI
- Australia Employment Change for October 2026 at 12:30 am GMT Thursday, Nov. 19: forecasts call for about 34K new jobs after a 39.3K drop, with the jobless rate seen at 4.7%. A rebound could revive RBA hike bets after Wednesday’s hot wage data. Premium members can read the Australia employment Event Guide.
- U.S. Initial Jobless Claims and Philadelphia Fed Manufacturing Index at 1:30 pm GMT Thursday, Nov. 19: claims are seen at 197K after 200K, and the Philly Fed index at 20.0 after 20.9. Firm numbers could add weight to the Fed’s hike talk.
- Japan Inflation Rate for October 2026 at 11:30 pm GMT Thursday, Nov. 19: prices rose 2.1% y/y in September. A firm print could back Ueda’s case for a December BOJ hike.
Also on the calendar (GMT):
- New Zealand Balance of Trade for October 2026 at 9:45 pm GMT Wednesday
- Japan Machinery Orders for September 2026 at 11:50 pm GMT Wednesday
- Anthropic’s IPO pricing, expected after the U.S. close at 9:00 pm GMT Wednesday
- U.S. 10-year TIPS auction at 6:00 pm GMT Thursday
- U.K. Retail Sales for October 2026 at 7:00 am GMT Friday, Nov. 20
Australia’s jobs data could show whether hot wages turn into a stronger Aussie, while U.S. claims and Anthropic’s IPO may decide if the dollar’s hike-driven run has more room.
Prefer email updates? The Babypips Daily Newsletter sends market news and trading best practices to your inbox.
Stay frosty out there, forex friends!