Financial & Forex Market Recap: Nov. 17, 2026
On Nov. 17, 2026, a tech selloff before Nvidia’s earnings sank U.S. stocks, Treasuries caught a safe-haven bid, and the dollar faded from a 19-month high.
Tech stocks took another beating on Tuesday as traders waited for Nvidia’s first earnings report since Jensen Huang’s exit, and the S&P 500 fell about 1% for a fourth straight loss. The U.S. dollar hit a fresh 19-month high after strong core retail sales and hawkish Fed talk, then gave the gain back as the 10-year Treasury yield slipped on safe-haven buying. Bitcoin lost about 2%, while gold and oil ended close to flat.
In short: On Tuesday, Nov. 17, 2026, a tech selloff before Nvidia’s earnings pulled the S&P 500 down about 1.0% to near 7,342. Safe-haven buying eased the 10-year Treasury yield to near 5.11%, and the Dollar Index slipped 0.1% to near 103.51 after touching a 19-month high. Bitcoin fell 1.9% to near $63,915.
Tuesday’s Market Scoreboard: Stocks and Bitcoin Slide as the Pound Leads
| Asset | Close (approx.) | Day change | Driver |
|---|---|---|---|
| S&P 500 | 7,342 | -0.99% | Tech, software selloff before Nvidia |
| U.S. 10-year yield | 5.11% | -0.35% (about -2 bp) | Safe-haven bid beat hawkish Fed |
| U.S. Dollar Index | 103.51 | -0.08% | Faded after 19-month high |
| WTI crude oil | $85.80 | +0.16% | Tanker attacks vs. surplus outlook |
| Gold | $3,848 | -0.19% | High yields cap rebound |
| Bitcoin | $63,915 | -1.90% | Tracked tech stocks lower |
| USD/JPY | 159.34 | -0.06% | Mild safe-haven yen bid |
| EUR/USD | 1.1008 | +0.09% | ZEW beat, dollar fade |
| GBP/USD | 1.3210 | +0.19% | Jobless rate dip, rebound |
| USD/CHF | 0.8400 | +0.00% | Steady after dollar peak |
| AUD/USD | 0.6736 | -0.03% | Risk-off, split RBA minutes |
| NZD/USD | 0.5496 | -0.09% | Risk-off, low yield edge |
| USD/CAD | 1.4293 | -0.04% | Steady oil, softer dollar |
Approximate levels, 6:00 pm ET Monday to 4:00 pm ET Tuesday. Drivers are likely factors, not confirmed causes.
Forex News Headlines & Data: U.S. Retail Sales, U.K. Jobs, RBA Minutes and Fed Talk
- The Reserve Bank of Australia (RBA) November meeting minutes showed six of nine members judged this year’s rate hikes not “clearly sufficient” to tame inflation, while three warned of a sharper downturn
- New Zealand RBNZ Inflation Expectations 1 Year for Q4 2026: 2.92% (2.60% previous)
- U.K. Unemployment Rate for September 2026: 4.6% (4.7% forecast; 4.7% previous)Below forecast
- Average Earnings excl. Bonus: 3.5% y/y (3.6% forecast; 3.7% previous)Below forecast
- Employment Change: 156K (136K forecast; 102K previous)Above forecast
- HMRC Payrolls Change for October: -34K (20K previous)
- Germany ZEW Economic Sentiment for November 2026: 35.6 (29.0 forecast; 28.1 previous)Above forecast
- Euro area ZEW Economic Sentiment: 26.5 (18.5 previous)
- Iranian drones launched at a U.S. radar site in Bahrain were intercepted with no damage, the U.S. military said, as tankers came under fresh attack near the Strait of Hormuz
- St. Louis Fed President Alberto Musalem said the economy will likely need “several interest rate increases” before spring 2027
- Canada Housing Starts for October 2026: 244.6K (238.0K forecast; 250.1K previous)Above forecast
- U.S. Retail Sales for October 2026: 0.2% m/m (0.2% forecast; 0.8% previous)In line
- Retail Sales Ex Autos: 0.6% m/m (0.4% forecast; 1.1% previous)Above forecast
Why it mattered: Spending outside autos beat forecasts, a sign households kept buying despite high prices, which may keep the Fed on track to hike. The dollar and yields jumped right after the 8:30 am ET release, then faded.
- U.S. Import Prices for October 2026: 1.1% m/m (0.7% forecast; 1.1% previous)Above forecast
- Export Prices: 1.1% m/m (0.5% forecast; 2.4% previous)Above forecast
- U.S. Industrial Production for October 2026: -0.4% m/m (0.1% forecast; 0.7% previous)Below forecast
- U.S. NAHB Housing Market Index for November 2026: 25 (29 forecast; 29 previous)Below forecast
- New York Fed President John Williams said the Fed will likely need to raise rates again but sees no need for “dramatic action”
Broad Market Price Action: Tech Selloff Deepens Before Nvidia’s Report
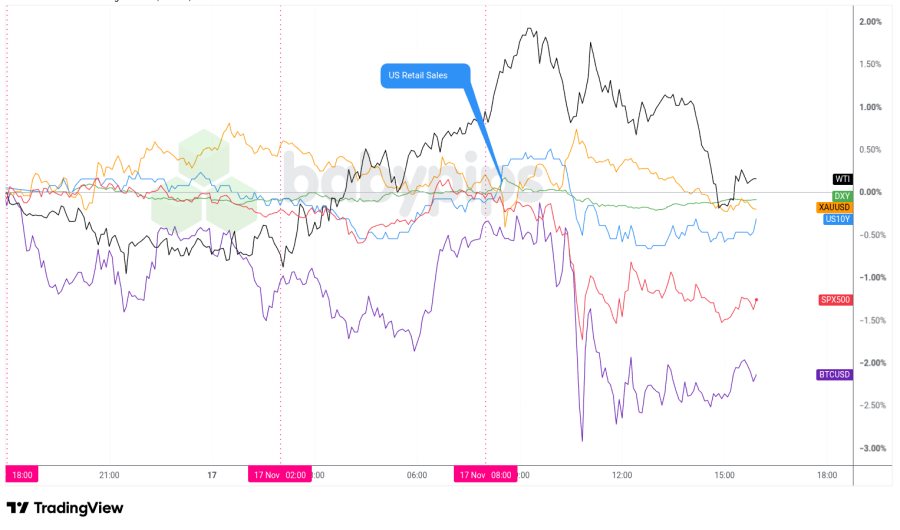
The tech scare spread wider. The cash S&P 500 fell 1.0% to 7,341 for its first four-day losing streak since September, and it swung to a loss of as much as 1.7% during the day. Traders likely cut risk before Nvidia’s results after the bell, its first report since Huang left. Software stocks fell hard too. A string of tech outages, most recently at the National Security Agency, probably fed worries about software security, and Salesforce slid more than 9% at one point. Nvidia itself closed only 0.4% lower after Huang said he’d be willing to return.
U.S. data gave mixed signals. Spending outside autos beat forecasts, and import prices jumped 1.1%, with capital goods import prices posting their biggest rise since the series began in 1988. Musalem added that several more hikes may be needed. That combo likely pushed the dollar to its 19-month high near 103.77 around 8:35 am ET. But factory output fell and homebuilder confidence sank to its lowest since April 2012, which may have reminded traders that higher rates are already biting.
Treasuries won the tug of war. The 10-year yield slipped about 2 basis points to near 5.11%, likely because money ran from stocks into bonds as the selloff deepened. Rate bets barely moved. CME FedWatch showed a 95.4% chance of a quarter-point Fed hike in December as of Tuesday’s close.
Oil got squeezed from both sides. WTI rose about 0.2% to near $85.80 as tanker attacks near Hormuz and expected U.S. stock draws kept buyers interested, while a supply surplus outlook capped gains. Gold slipped about 0.2% to near $3,848, just above Monday’s 13-month low. High yields and a firm dollar probably kept buyers away, since gold pays no interest.
Bitcoin fell about 1.9% to near $63,915 and mostly tracked tech stocks lower. Market maker Wintermute warned it could slide into the $50,000s, pointing to Fed hike bets and a 10-year yield above 5%.
Market concept of the dayWhy Can Bond Yields Fall When the Fed Sounds Hawkish?
Hawkish Fed talk usually pushes yields up, because traders expect higher rates. But when stocks drop fast, many investors move cash into Treasuries, which they see as one of the safest places to park money. That buying lifts bond prices and pushes yields down. On Tuesday, the safe-haven pull likely outweighed Musalem’s hike talk, which you can learn more about in Risk-On / Risk-Off: How Market Mood Moves Currencies in the School of Pipsology.
FX Market Behavior: U.S. Dollar vs. Majors
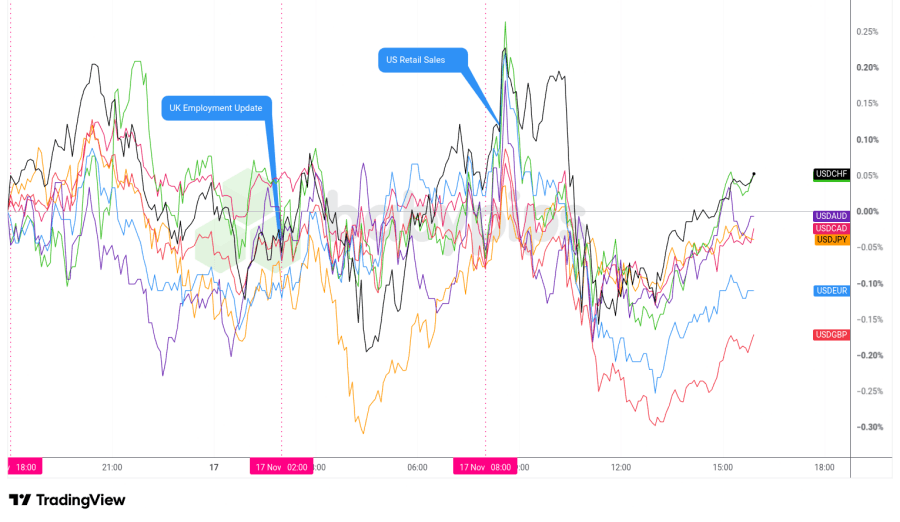
The U.S. dollar ended mixed and the Dollar Index slipped about 0.1% to near 103.51. The British pound was the strongest major, up about 0.2% to near 1.3210, and the euro added about 0.1%. The yen and Canadian dollar edged higher, and the Swiss franc was flat. The New Zealand dollar was the weakest major, down about 0.1%, and the Australian dollar slipped slightly.
The dollar’s early pop probably came from the hot data and Musalem’s remarks, which kept a December hike close to certain. It faded as yields eased during the stock selloff, and Williams later pushed back on the idea of bigger moves. Traders have also trimmed bets on a half-point hike since last week, which may have taken some air out of the dollar’s six-day run.
The pound likely got help from a surprise drop in the U.K. jobless rate, though slower wage growth limited the lift. A bounce after a nearly 2% slide over the past five days and positioning before Wednesday’s inflation report may also explain its gains. The euro touched a 19-month low early, then recovered as the dollar softened and Germany’s ZEW survey beat forecasts.
The kiwi and Aussie struggled with the risk-off mood. The kiwi hit a 19-month low near $0.5492, and with no major catalysts to point to, New Zealand’s rate disadvantage to Australia may have been the driver. The RBA minutes leaned hawkish, but the 6-3 split may have convinced traders that Australian rates have peaked. The yen held up as a safe haven, and wariness about possible intervention near 160 per dollar probably kept a lid on USD/JPY.
On Premium this weekThis week’s Fundies Cheat Sheet lays out the week’s big tests, from Tuesday’s retail sales and Nvidia’s report to Wednesday’s U.K. inflation data and Fed minutes. It’s part of Babypips Premium.
Upcoming Potential Catalysts on the Economic Calendar: U.K. CPI, Fed Minutes and Nvidia
- U.K. CPI for October 2026 at 7:00 am GMT Wednesday, Nov. 18: economists expect 3.6% y/y after 3.5%, with core prices seen up 0.3% m/m. A hot print could support Bank of England hike bets and the pound. Premium members can read the U.K. CPI Event Guide.
- FOMC Meeting Minutes at 7:00 pm GMT Wednesday, Nov. 18: traders will look for clues on how many more hikes the Fed has in mind after its October meeting.
- Nvidia third-quarter earnings after the U.S. close Tuesday, Nov. 17 (call at 10:00 pm GMT):analysts expect about $109.1 billion in revenue. The outlook and leadership update could decide whether the tech selloff finds a floor.
Also on the calendar (GMT):
- U.S. API Crude Oil Stock Change at 9:30 pm GMT Tuesday
- Japan Balance of Trade for October 2026 at 11:50 pm GMT Tuesday
- U.S. Building Permits and Housing Starts for October 2026 at 1:30 pm GMT Wednesday
- U.S. 20-year Treasury bond auction at 6:00 pm GMT Wednesday
Nvidia’s numbers after the bell may set the tone for stocks, the Aussie and Bitcoin into Wednesday. Then U.K. inflation, the Fed minutes and Anthropic’s IPO pricing could decide whether the dollar takes another run at its highs.
Prefer email updates? The Babypips Daily Newsletter sends market news and trading best practices to your inbox.
Stay frosty out there, forex friends!