Financial & Forex Market Recap: Nov. 10, 2026


Tuesday, Nov. 10, 2026: A hot U.S. CPI report and hawkish Fed talk lifted the 10-year yield near 4.99%, gold fell 2.5%, and the U.S. dollar beat every major.
Inflation worries ran Tuesday’s markets. Federal Reserve Governor Christopher Waller floated a half-point December rate hike hours before October’s U.S. Consumer Price Index (CPI) beat forecasts, and the 10-year Treasury yield jumped about 10 basis points to near 4.99%. The U.S. dollar rose against every major, gold fell about 2.5%, Bitcoin hit a nearly three-month low, the S&P 500 slipped 0.4% as Nvidia sank again, and oil eased as Washington played down new strikes on Iran.
In short: On Tuesday, Nov. 10, 2026, a hotter-than-expected U.S. CPI report and hawkish Fed comments likely pushed the 10-year Treasury yield up about 10 basis points to near 4.99%. The Dollar Index rose 0.6% to near 102.26, gold fell 2.5% to near $4,032, Bitcoin lost 1.7%, and the S&P 500 slipped 0.4% to near 7,524.
Tuesday’s Market Scoreboard: Yields Jump, Gold Drops and the Dollar Climbs
| Asset | Close (approx.) | Day change | Driver |
|---|---|---|---|
| S&P 500 | 7,524 | -0.4% | Hot CPI, Nvidia slide |
| U.S. 10-year yield | 4.99% | +2.1% (about +10 bp) | Hot CPI, hawkish Fed speakers |
| U.S. Dollar Index | 102.26 | +0.6% | Higher yields, Fed hike bets |
| WTI crude oil | $86.84 | -0.3% | U.S. plays down Iran strikes |
| Gold | $4,032 | -2.5% | Higher yields, firmer dollar |
| Bitcoin | $73,766 | -1.7% | Risk-off, Fed hike bets |
| USD/JPY | 158.81 | +0.6% | Wider U.S. yield advantage |
| EUR/USD | 1.1166 | -0.5% | Broad dollar strength |
| GBP/USD | 1.3344 | -0.7% | Broad dollar strength |
| USD/CHF | 0.8254 | +0.7% | Yields outweighed haven demand |
| AUD/USD | 0.6868 | -0.8% | Weak local surveys, risk-off |
| NZD/USD | 0.5604 | -0.5% | Smallest loss among majors |
| USD/CAD | 1.4189 | +0.5% | Broad dollar strength |
Approximate levels, 6:00 pm ET Monday to 4:00 pm ET Tuesday. Drivers are likely factors, not confirmed causes.
Forex News Headlines & Data: U.S. CPI, Fed Speakers, China Trade and Iran
- Japan Household Spending for September 2026: -6.8% y/y (-3.1% y/y forecast; -3.1% y/y previous)Below forecast
- The Westpac-Melbourne Institute Consumer Sentiment Index for Australia fell 2.7% to 78.2 in November 2026, its lowest reading in four years
- U.K. BRC Like-for-Like Retail Sales for October 2026: 1.1% y/y (1.2% y/y forecast; 1.0% y/y previous)Below forecast
- Australia NAB Business Confidence for October 2026: -15 (-14 forecast; -14 previous)Below forecast
- NAB Business Conditions: -2 (-1 previous)
- China Balance of Trade for October 2026: $105.28B ($125.8B forecast; $133.53B previous)Below forecast
- Exports: 35.2% y/y (33.5% y/y forecast; 36.3% y/y previous)Above forecast
- Imports: 41.6% y/y (32.0% y/y forecast; 31.0% y/y previous)Above forecast
- U.S. President Donald Trump said Qatar, Saudi Arabia, the UAE, Bahrain and Kuwait would “prefer the status quo,” which keeps the U.S. naval blockade of Iran in place without new major strikes
- Fed Governor Christopher Waller said he would support a 25 basis point hike in December even if October inflation improved, and that a 50 basis point hike should be considered if core CPI came in around 0.3% or higher
- U.S. NFIB Business Optimism Index for October 2026: 97.8 (97.6 forecast; 97.9 previous)Above forecast
- U.S. CPI for October 2026: 0.4% m/m (0.3% m/m forecast; 0.6% m/m previous)Above forecast
- Core CPI: 0.3% m/m (0.2% m/m forecast; 0.3% m/m previous)Above forecast
Why it mattered: Core inflation landed right on the 0.3% threshold Waller had named that morning, so traders added to bets on a December Fed hike, possibly a larger one, and short-term Treasury yields jumped. The Bureau of Labor Statistics did not publish an annual rate because of data gaps from last year’s government shutdown.
- Secretary of State Marco Rubio told Group of Seven (G7) allies that U.S. sanctions and the naval blockade are working well enough that President Trump does not need major combat operations against Iran
- Dallas Fed President Lorie Logan suggested that the Federal Open Market Committee (FOMC) needs at least two more 25-basis-point rate increases and that it may be possible to move faster this winter
- Nvidia shares fell about 5.5% for a second straight day as investors weighed the fallout from CEO Jensen Huang’s affair with an alleged Chinese spy
- Iran’s top security official Mohsen Rezaei said no negotiations are taking place between Tehran and Washington
- The U.S. Treasury sold $42 billion of 10-year notes at a 5.020% high yield (5.300% at the October sale), with a bid-to-cover ratio of 2.46 (2.77 previous)
- Fed Vice Chair for Supervision Michelle Bowman said “there is still work to do” to bring inflation closer to 2% and flagged the risk of “a large correction in equity valuations” if returns on AI investment fall short
- Bitcoin miner MARA said it sold 13,597 BTC for about $1.1 billion after the end of the third quarter and expects to keep selling
Broad Market Price Action: Hot CPI and a Hawkish Fed Lift Yields as Gold Slides
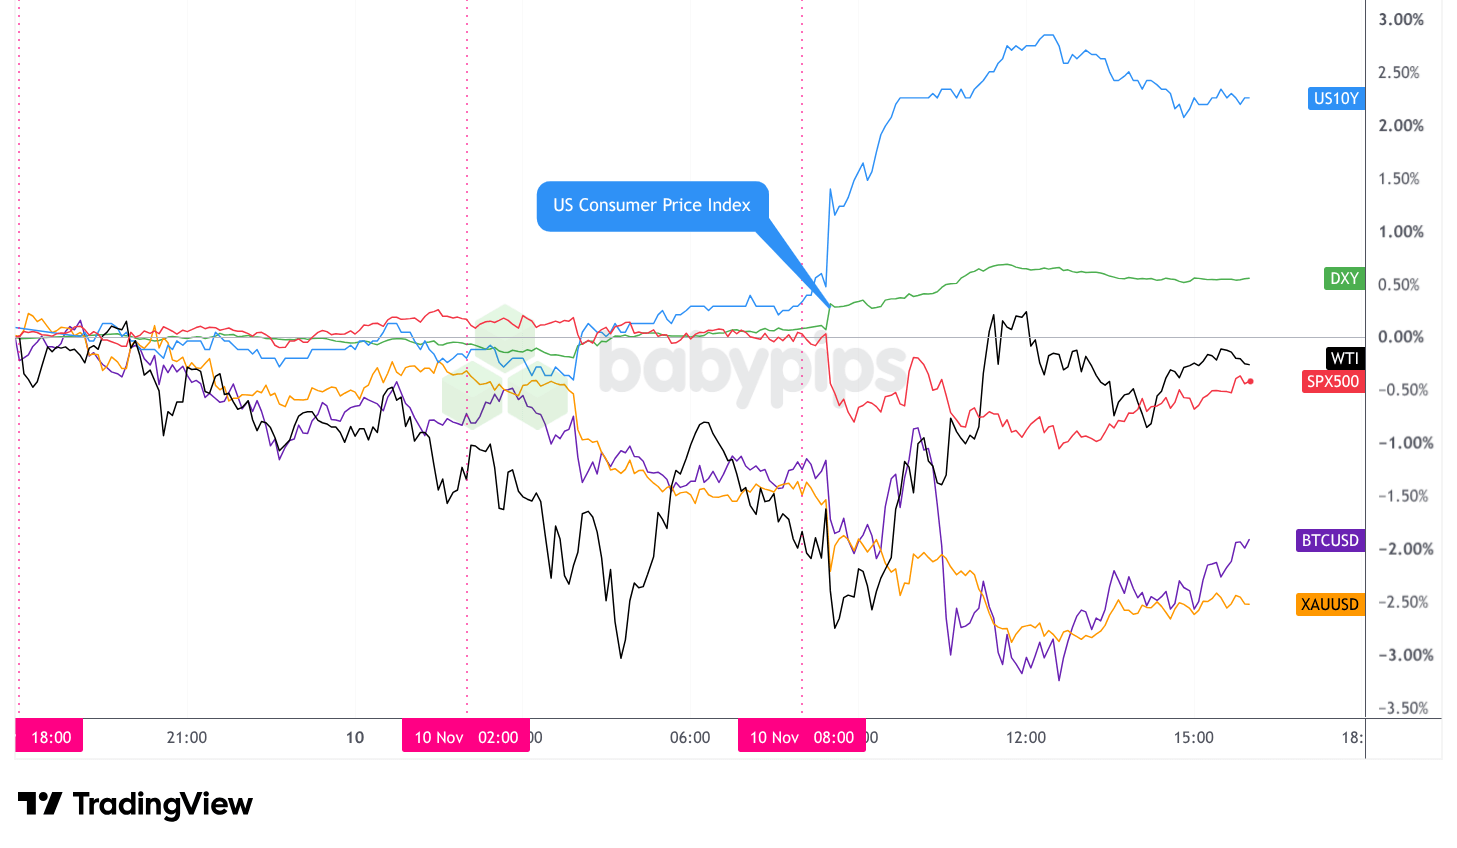
Rate expectations drove most of Tuesday’s moves. Speaking in London around 4:00 am ET, Fed Governor Christopher Waller said he would back a quarter-point hike in December even if inflation improved, and that a 50 basis point move should be considered if core CPI rose around 0.3% or more. The October CPI report then showed core prices up exactly 0.3%. The 2-year Treasury yield, which tracks Fed expectations most closely, jumped more than 18 basis points, and the 10-year Treasury yield rose about 10 basis points to near 4.99% after briefly topping 5%. A soft 10-year note auction at 1:00 pm ET likely added to the pressure on bonds.
Premium members got the U.S. CPI Event Guide ahead of Tuesday’s release.
Other Fed officials leaned the same way. Dallas Fed President Lorie Logan said the Fed needs “at least two more” quarter-point hikes, possibly at a faster pace this winter, and Fed Vice Chair for Supervision Michelle Bowman said “there is still work to do” on inflation in a 3:30 pm ET speech. By the close, money markets probably treated a December hike as close to certain, with some chance of a half-point move.
Higher yields and a firmer dollar likely did most of the damage to gold, which pays no interest and fell about 2.5% to near $4,032. Bitcoin dropped about 1.7% to near $73,770 after it slipped below $73,000 for the first time since August. The rate outlook probably weighed on crypto along with stocks, and MARA’s disclosure of large bitcoin sales may have added to the gloom. The S&P 500 brushed off CPI at the open but turned lower by mid-morning as Nvidia fell about 5.5% for a second day, and it finished down about 0.4% near 7,524. Rising yields likely made richly valued tech shares harder to hold.
WTI crude oil eased about 0.3% to near $86.84 after a wide swing. Trump said Gulf allies “prefer the status quo” of a blockade without new major strikes, and Secretary of State Marco Rubio told G7 allies that major combat operations are not needed. Both comments likely shaved some of the war premium out of crude. Oil probably recovered part of its drop after Iran’s top security official said no talks with Washington are underway, which suggested a deal is still some way off.
Market concept of the dayWhy Did the 2-Year Yield Jump More Than the 10-Year?
The 2-year Treasury yield mostly reflects where traders expect the Fed’s policy rate to sit over the next couple of years, so a hot inflation print that raises hike odds hits it hardest. The 10-year also prices in longer-run views on growth and inflation, so it usually moves less. On Tuesday the 2-year rose more than 18 basis points while the 10-year gained about 10, and those higher short-term yields likely widened the dollar’s yield advantage over the other majors. You can learn how that link works in How Bond Yields Affect Currency Movements.
FX Market Behavior: U.S. Dollar vs. Majors
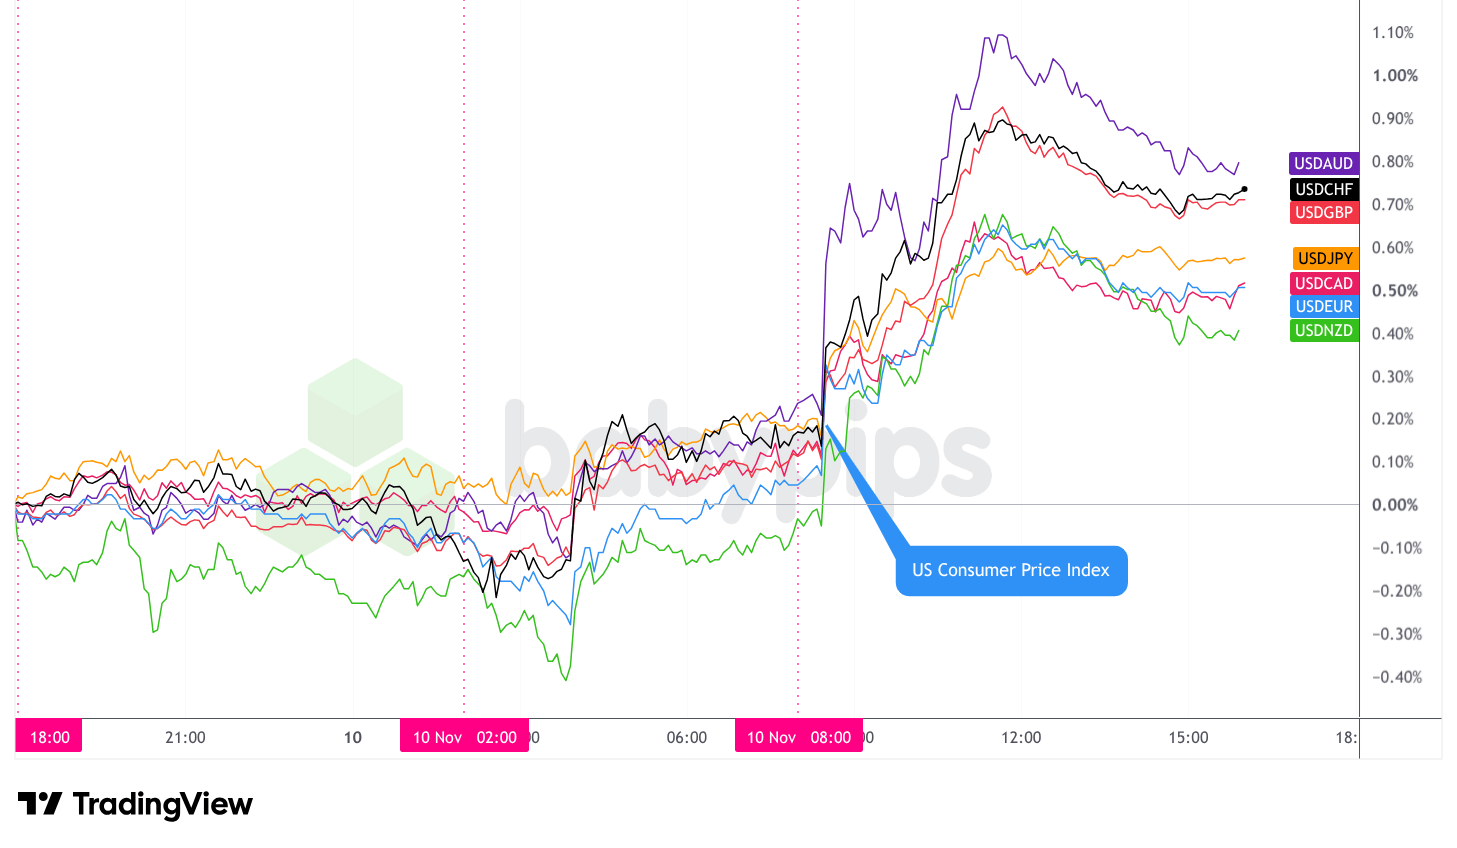
The U.S. dollar rose against all seven majors, and the Dollar Index gained about 0.6% to near 102.26. The Australian dollar finished as the weakest major, down about 0.8%, followed by the Swiss franc and the British pound at about 0.7% each. The yen lost about 0.6%, while the euro, the Canadian dollar and the New Zealand dollar each slipped about 0.5%, with the kiwi holding up best.
The dollar’s gains lined up with the rate story. It was already firming after Waller’s speech, before the 8:30 am ET CPI release, and it extended those gains as short-term Treasury yields climbed. A Fed that may hike in December, and possibly by half a point, raises the return on dollar deposits relative to most other majors.
The yen fell about 0.6%, and USD/JPY ended near 158.81, close to its high of the day. The wider gap between U.S. and Japanese yields likely outweighed talk of a Bank of Japan (BOJ) hike, and Japanese household spending fell 6.8% from a year earlier in September, which may raise doubts about how fast the BOJ can move.
The Australian dollar likely took an extra hit from weak local surveys and the risk-off mood. Westpac’s consumer sentiment index sank to a four-year low, NAB business confidence slipped, and China’s trade surplus came in well short of forecasts even though exports beat. The franc’s 0.7% drop suggests higher U.S. yields mattered more than safe-haven demand, and falling gold may have weighed on both the franc and the Aussie. The euro, the pound and the loonie mostly tracked the broad dollar, with no major local data to lean on.
On Premium this weekTuesday’s CPI report was the first of two inflation tests that this week’s Fundies Cheat Sheet lined up, with U.S. producer prices due Friday. The Cheat Sheet also flags the AI earnings that continue on Thursday with Cisco and Applied Materials. It’s part of Babypips Premium.
Upcoming Potential Catalysts on the Economic Calendar: U.S. Bond Holiday, U.K. GDP and U.S. PPI
- U.S. Veterans Day bond market holiday on Wednesday, Nov. 11 (full day): U.S. dollar fixed income trading will be closed while U.S. stock markets stay open, so Treasury trading may thin out after Tuesday’s jump in yields.
- U.K. GDP Growth Rate Prel for Q3 2026 at 7:00 am GMT Thursday, Nov. 12: forecasts call for 0.7% q/q after 0.4% in Q2, and the release is the pound’s biggest data test of the week and may shift Bank of England rate expectations.
- U.S. PPI for October 2026 at 1:30 pm GMT Friday, Nov. 13: economists expect 0.4% m/m after 1.3% in September. Producer prices are the last big inflation read this week before the Fed’s Dec. 8-9 meeting.
Also on the calendar (GMT):
- Japan Reuters Tankan Index for November 2026 at 11:00 pm GMT Tuesday
- Fed Vice Chair for Supervision Bowman Speech at 11:30 pm GMT Tuesday
- Australia Home Loans for Q3 2026 at 12:30 am GMT Wednesday
- Germany Inflation Rate Final for October 2026 at 7:00 am GMT Wednesday
- Japan PPI for October 2026 at 11:50 pm GMT Wednesday
- U.S. Initial Jobless Claims at 1:30 pm GMT Thursday
- U.S. Existing Home Sales for October 2026 at 3:00 pm GMT Thursday
- U.S. EIA Crude Oil Inventories at 5:00 pm GMT Thursday, a day later than usual
- U.S. 30-Year Bond Auction at 6:00 pm GMT Thursday
- Cisco and Applied Materials earnings on Thursday
- Euro area Employment Change Prel for Q3 2026 at 10:00 am GMT Friday
With a December hike looking close to locked in, Friday’s producer prices may decide how much room is left for talk of a half-point move. Wednesday’s bond market holiday could make for thinner dollar trading in the meantime, and any official word from Washington or Tehran on talks may matter more for oil than for the Fed.
Prefer email updates? The Babypips Daily Newsletter sends market news and trading best practices to your inbox.
Stay frosty out there, forex friends!
Disclaimer: This article is for educational purposes only. It isn’t investment or trading advice or a recommendation to trade. Prices, levels, and percentage moves here are approximate because the market data was not captured at the exact close. The explanations for market moves are possible reasons, not confirmed causes.
AI disclosure: The Babypips editorial team used AI tools to help research, write, and check this article. A Babypips editor reviewed and edited it before publication. AI tools can misread data, make arithmetic errors, and state wrong information in a confident tone. Check figures and quotes against the linked sources before you rely on them. Our Editorial Policy explains how we create and review our content.