Financial & Forex Market Recap: Nov. 4, 2026


On Wednesday, Nov. 4, 2026, a Democratic sweep of Congress sank oil 8.5%, sent the dollar lower and lifted gold above $4,000 as stocks recovered.
Democrats swept both chambers of Congress in Tuesday’s U.S. midterms, and Wednesday’s markets likely traded the result as a check on the Iran war. The dollar fell against every major, and WTI crude oil sank about 8.5% after Vice President JD Vance blamed the war for his party’s losses. The S&P 500 shook off early tech selling to finish about 1.4% higher, gold climbed back above $4,000 and the 10-year Treasury yield eased to about 4.89%.
In short: On Wednesday, Nov. 4, 2026, Democrats won both chambers of Congress, and markets appeared to price a lower Iran war premium. WTI crude oil sank about 8.5% to near $89.37, the dollar index fell 0.4% to 101.51, and gold rose 3.3% to near $4,063. The S&P 500 gained about 1.4% and the 10-year yield eased to about 4.89%.
Wednesday’s Market Scoreboard: Oil Plunges, Dollar Slides and Gold Tops $4,000
| Asset | Close (approx.) | Day change | Driver |
|---|---|---|---|
| S&P 500 | 7,695.7 | +1.4% | Post-midterm relief, tech rebound |
| U.S. 10-year yield | 4.89% | -1.2% (about -6 bp) | Gridlock, cheaper oil eased yields |
| U.S. Dollar Index | 101.51 | -0.4% | Democratic sweep dollar selling |
| WTI crude oil | $89.37 | -8.5% | War-end talk after midterms |
| Gold | $4,063 | +3.3% | Weaker dollar, lower yields |
| Bitcoin | $80,076 | +3.0% | Risk-on rebound |
| USD/JPY | 158.46 | -0.1% | Early dollar drop mostly reversed |
| EUR/USD | 1.1232 | +0.4% | Broad dollar weakness |
| GBP/USD | 1.3472 | +0.5% | Dollar weakness before BoE |
| USD/CHF | 0.8169 | -0.5% | Franc firmed as dollar slid |
| AUD/USD | 0.7011 | +0.6% | Risk-on, weaker dollar |
| NZD/USD | 0.5625 | +0.7% | Dollar selling outweighed jobless jump |
| USD/CAD | 1.3963 | -0.3% | Dollar weakness despite oil drop |
Approximate levels, 6:00 pm ET Tuesday to 4:00 pm ET Wednesday. Drivers are likely factors, not confirmed causes.
Forex News Headlines & Data: U.S. Midterms, Euro Area CPI, U.S. ISM Services and NZ Jobs
- Democrats won control of both the House and the Senate in Tuesday’s U.S. midterm elections, setting up divided government; Reuters reported that Treasuries rallied on expectations that gridlock may limit government spending, and that the dollar index fell to 101.21 at one point, its lowest since Sept. 30
- Vice President JD Vance said on social media that “the reason we lost is the war,” and Sen. Chuck Schumer, the likely Senate majority leader in the next Congress, vowed that Democrats will push to end the war; Reuters reported that Trump acknowledged the Iran war played a role in his party’s defeat
- New Zealand Unemployment Rate for Q3 2026: 5.7% (5.5% forecast; 5.6% previous)Above forecast; RNZ said it was the highest in nearly 11 years
- Australia Household Spending for Q3 2026: 0.7% q/q (no forecast; 0.7% previous)
- China RatingDog General Services PMI for October 2026: 50.8 (no consensus found; 51.6 previous)
- Euro Area Inflation Rate Flash for October 2026: 4.0% y/y (4.0% forecast; 3.8% previous)In line; core inflation held at 2.5% y/y (2.5% forecast; 2.5% previous) and energy inflation rose to 20.8%
Why it mattered: headline inflation hit 4% for the first time since 2023 on energy costs, which keeps an ECB hike in December in play, but steady core inflation may have limited the boost to the euro. - U.S. ADP Employment Change for October 2026: 86K (69K forecast; 86K previous)Above forecast
- U.S. Trade Balance for September 2026: -$105.0B (-$108.0B forecast; -$105.7B previous)Above forecast
- Canada Merchandise Trade Balance for September 2026: C$5.4B (C$4.1B forecast; C$5.0B previous)Above forecast
- ISM Services PMI for October 2026: 54.5 (54.8 forecast; 54.9 previous)Below forecast; new orders slipped to 55.9 from 59.8
- U.S. EIA Crude Oil Inventories for the week ended Oct. 30: -0.9M barrels (+1.75M forecast; -1.9M previous)Below forecast
Broad Market Price Action: Democratic Sweep Drains Oil’s War Premium as Stocks Recover
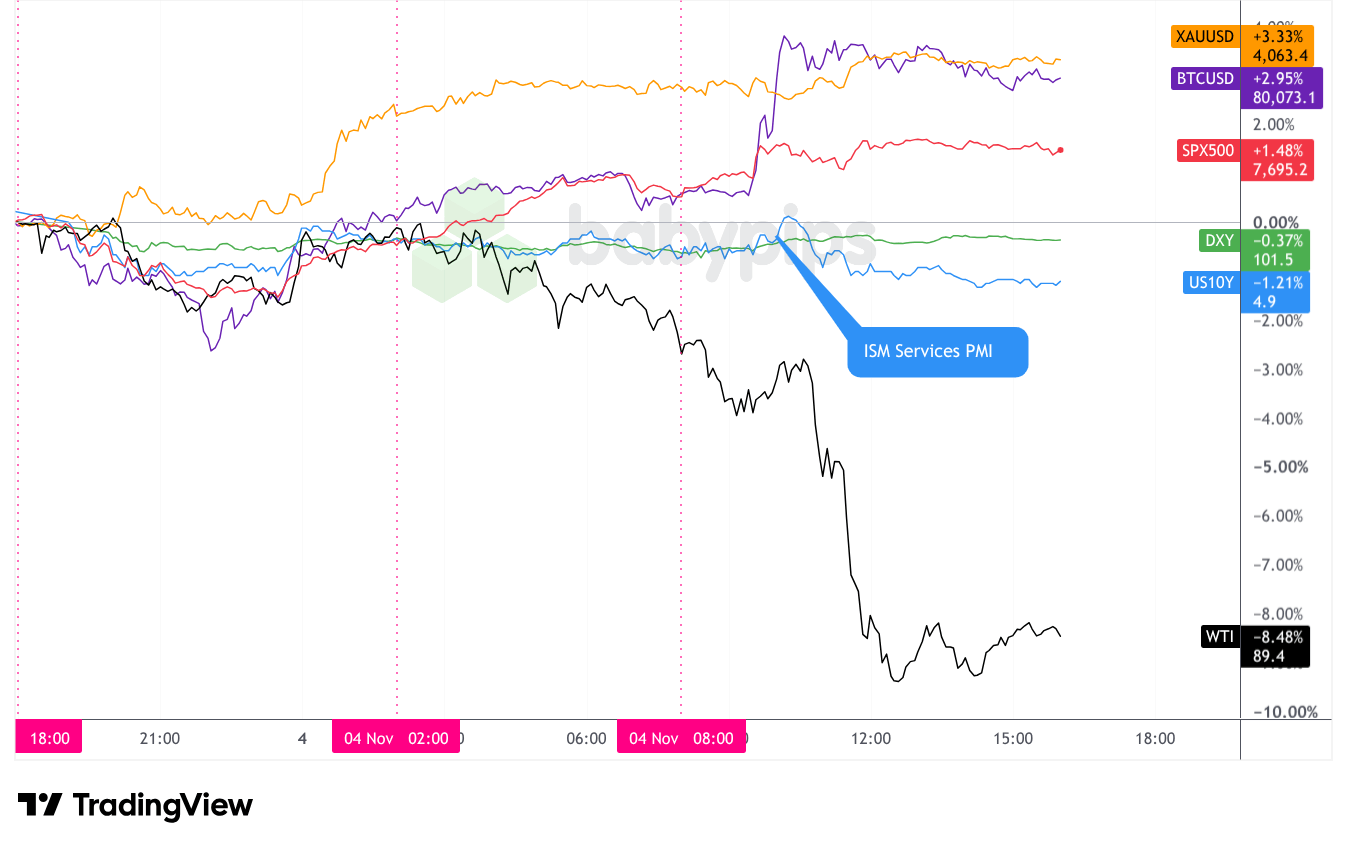
Election projections likely hit stocks first. As projections showed Democrats winning Senate seats and then the House on Tuesday evening, U.S. stock futures slid, with chip and AI names leading. Traders appeared to worry that a Democratic Congress could slow data center construction and AI spending. By Wednesday’s cash session the selling had reversed, and Reuters reported that investors welcomed a clear result and the prospect of gridlock. The S&P 500 finished about 1.4% higher near 7,696.
Oil probably took the biggest hit from the vote. On Wednesday morning, Vance posted that “the reason we lost is the war,” and Schumer vowed to push to end it. Traders likely read both as raising the odds of a deal with Iran, which would ease the supply risk around the Strait of Hormuz. WTI fell about 8.5% to near $89.37, and CNBC reported that Brent settled at $94.62. A surprise draw in U.S. crude stocks would normally support prices, so the war headlines probably outweighed it.
Cheaper oil and the prospect of gridlock likely helped Treasuries too. Reuters said investors expect a divided Congress to limit government spending, and the 10-year yield eased about 6 basis points to near 4.89%. Lower yields and a softer dollar tend to support gold, and it jumped about 3.3% to near $4,063, back above $4,000. Bitcoin rose about 3.0% to near $80,076, probably tracking the broader risk-on rebound in stocks.
Market concept of the dayWhy Does a Weaker Dollar Often Lift Gold?
Gold is priced in U.S. dollars around the world, so when the dollar falls, gold gets cheaper for buyers using other currencies, and demand tends to rise. Lower Treasury yields help too, because gold pays no interest and looks less costly to hold when bond yields drop. On Wednesday, the dollar index slipped about 0.4% and the 10-year yield eased, and gold jumped about 3.3%. The link is a tendency, not a rule, and it has broken down before, as How Gold Affects AUD/USD and USD/CHF explains.
FX Market Behavior: U.S. Dollar vs. Majors
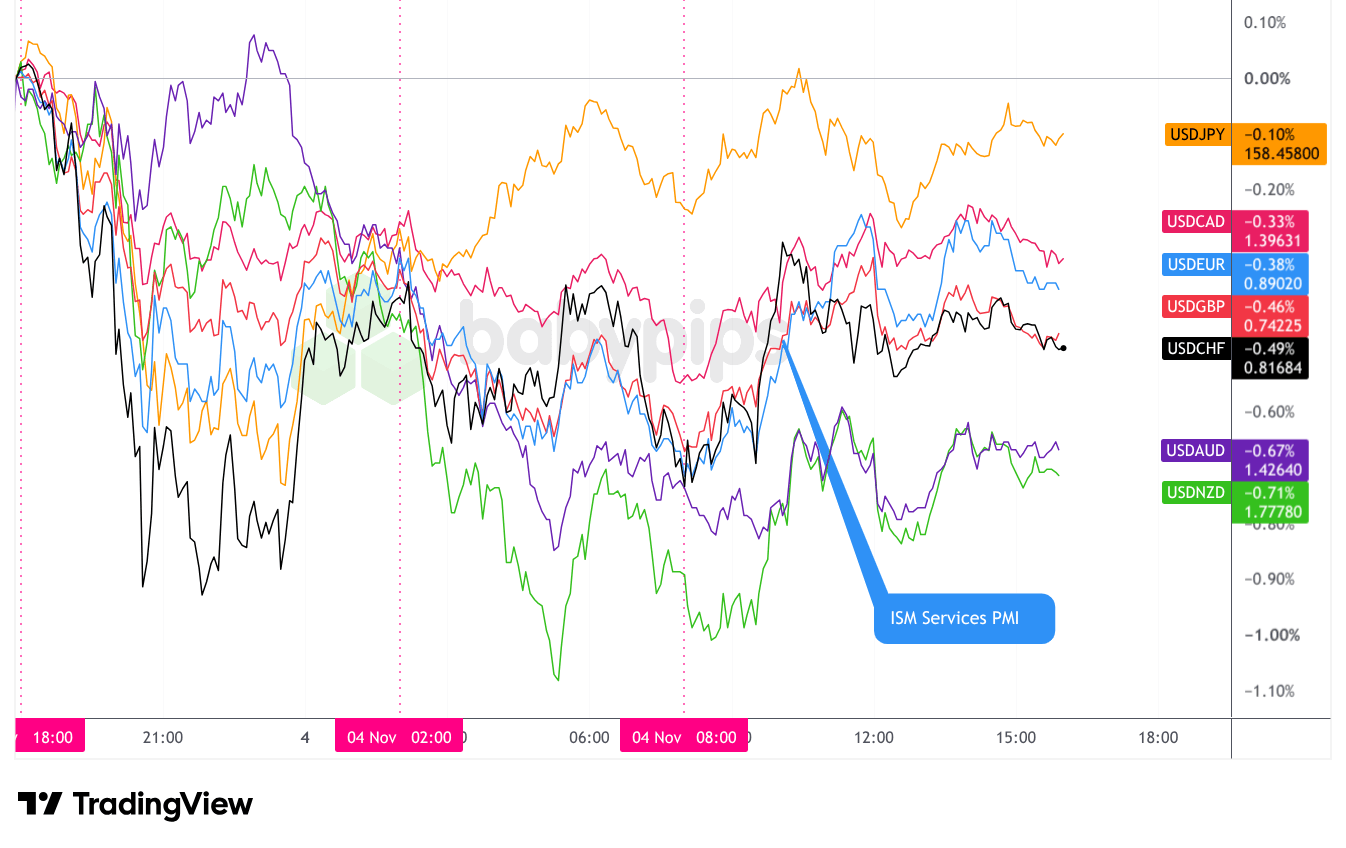
The dollar finished lower against every major. The New Zealand dollar led with a gain of about 0.7%, followed by the Australian dollar (+0.6%), the Swiss franc (+0.5%) and the pound (+0.5%). The euro rose about 0.4% and the Canadian dollar 0.3%, while the yen gained only about 0.1%.
Election projections probably drove most of the dollar’s drop. The dollar slid against all the majors at once as projections of Democratic Senate wins came in Tuesday evening, and Reuters reported that the dollar index fell as low as 101.21, its lowest since Sept. 30. Morningstar noted worries that tighter AI rules could slow U.S. growth, and lower Treasury yields also trimmed the dollar’s yield edge over its peers.
Risk-sensitive currencies likely got an extra lift from the rebound in stocks. The kiwi led even after New Zealand’s jobless rate rose to an 11-year high of 5.7%, which suggests the U.S. story outweighed fading bets on an RBNZ hike. The loonie lagged most of its peers, probably because the slide in oil clouded Canada’s export outlook despite a wider September trade surplus.
The yen barely gained. USD/JPY fell hard on the first projections but recovered most of the drop as stocks rallied, since a better risk mood tends to cut demand for the yen as a safe haven. The euro rose to about 1.1272 early, per Reuters, before giving back some gains, and euro area inflation at 4%, in line with forecasts, did little to change the ECB outlook.
On Premium this weekThis week’s Fundies Cheat Sheet: Nov. 2 to 6, 2026 flagged the midterms, Iran and Friday’s jobs report as the week’s big stories, and our Event Guide: BOE Monetary Policy Statement (November 2026) previews Thursday’s decision and how the pound might react. Both are part of Babypips Premium.
Upcoming Potential Catalysts: BoE Decision, U.S. Jobs Report and Canada Jobs
- Bank of England Interest Rate Decision at 12:00 pm GMT Thursday, Nov. 5: forecasts call for a hike to 4.00% from 3.75%, so the vote split and guidance on further hikes may matter more for the pound than the decision itself.
- U.S. Non-Farm Payrolls for October 2026 at 1:30 pm GMT Friday, Nov. 6: the TradingView calendar shows a 65K forecast against 29K previous, with the unemployment rate seen at 4.2%, and the report may test bets on a December Fed hike.
- Canada Unemployment Rate for October 2026 at 1:30 pm GMT Friday, Nov. 6: seen at 6.5% (6.5% previous); it lands alongside the U.S. report, so USD/CAD may react to both at once.
Also on the calendar (GMT):
- Australia Balance of Trade for September 2026 at 12:30 am GMT Thursday (A$0.81B forecast; A$0.50B previous)
- Bank of England Monetary Policy Report at 12:00 pm GMT Thursday
- U.S. Initial Jobless Claims at 1:30 pm GMT Thursday
- UoM U.S. Consumer Sentiment Prel for November 2026 at 3:00 pm GMT Friday (48.0 forecast; 46.3 previous)
- Canada Ivey PMI for October 2026 at 3:00 pm GMT Friday (58.2 previous, s.a.)
Prefer email updates? The Babypips Daily Newsletter sends market news and trading best practices to your inbox.
Stay frosty out there, forex friends!
Disclaimer: This article is for educational purposes only. It isn’t investment or trading advice or a recommendation to trade. Prices, levels, and percentage moves here are approximate because the market data was not captured at the exact close. The explanations for market moves are possible reasons, not confirmed causes.
AI disclosure: The Babypips editorial team used AI tools to help research, write, and check this article. A Babypips editor reviewed and edited it before publication. AI tools can misread data, make arithmetic errors, and state wrong information in a confident tone. Check figures and quotes against the linked sources before you rely on them. Our Editorial Policy explains how we create and review our content.
Related Articles
- Forex News
Financial & Forex Market Recap: Nov. 2, 2026
- Forex News
Financial & Forex Market Recap: Oct. 26, 2026
- Forex News
Financial & Forex Market Recap: Nov. 3, 2026
- Forex News
Financial & Forex Weekly Recap: October 19 – 23, 2026
- Economy News
Gold heads for biggest daily gain since August as dollar weakens