Financial & Forex Market Recap: Oct. 26, 2026


On Oct. 26, 2026, oil fell about 1.7% as Iran hosted talks in Tehran, gold held above $4,000, and Anthropic’s IPO filing lifted the S&P 500 about 0.7%.
Diplomacy took some heat out of oil on Monday. WTI crude oil fell about 1.7% to near $103 as Iran hosted Saudi, Pakistani and Turkish officials in Tehran, which likely eased inflation worries, nudged the 10-year Treasury yield down to near 4.99% and helped gold hold above $4,000. The S&P 500 added about 0.7% as Anthropic’s IPO filing lifted AI stocks, Bitcoin slipped about 0.4%, and the dollar still rose against every major ahead of five central bank decisions this week.
In short: On Monday, Oct. 26, 2026, WTI crude oil fell about 1.7% to near $103 as Iran hosted regional talks in Tehran, which likely eased inflation worries. The 10-year Treasury yield slipped to near 4.99%, gold rose 0.4% to near $4,013, and the S&P 500 gained 0.7% on Anthropic’s IPO filing. The dollar rose against all seven majors.
Monday’s Market Scoreboard: Oil, Gold, AI Stocks and a Firmer Dollar
| Asset | Close (approx.) | Day change | Driver |
|---|---|---|---|
| S&P 500 | 7,676 | +0.7% | Anthropic IPO filing lifted AI |
| U.S. 10-year yield | 4.99% | -0.3% (about -1 bp) | Softer oil eased inflation worries |
| U.S. Dollar Index | 102.0 | +0.2% | Broad bid before Fed week |
| WTI crude oil | $103.05 | -1.7% | Tehran talks vs. Saudi attacks |
| Gold | $4,013 | +0.4% | Softer oil, lower yields |
| Bitcoin | $79,870 | -0.4% | No clear catalyst |
| USD/JPY | 157.52 | +0.4% | Broad dollar bid in London |
| USD/CAD | 1.4020 | +0.1% | Swung with oil |
| EUR/USD | 1.1181 | -0.2% | Dollar bid outweighed France relief |
| GBP/USD | 1.3346 | -0.2% | Broad dollar bid |
| USD/CHF | 0.8276 | +0.3% | Franc slipped with the yen |
| AUD/USD | 0.7021 | -0.2% | Firmer dollar, CPI ahead |
| NZD/USD | 0.5685 | -0.3% | Firmer dollar, RBNZ ahead |
Approximate levels, 6:00 pm ET Sunday to 4:00 pm ET Monday. Drivers are likely factors, not confirmed causes.
Forex News Headlines & Data: Iran Talks, Anthropic IPO, Ifo and Dallas Fed
- High-level delegations from Saudi Arabia, Pakistan and Turkey met Iranian officials in Tehran to try to avert renewed fighting, while further Houthi attacks on Saudi Arabia kept supply concerns alive
- Anthropic publicly filed for a Nasdaq IPO under the ticker ANT, with the SEC accepting the S-1 at about 9:00 am ET; the filing showed a first-half net loss of $80.7 billion
- Meta said it plans to raise up to $95 billion in equity to fund its AI data center expansion
- French government bonds rallied after Moody’s kept France’s Aa3 credit rating late Friday
- Brazil’s real tumbled after President Luiz Inacio Lula da Silva won a fourth term in Sunday’s runoff
- Reserve Bank of Australia Assistant Governor Brad Jones: valuations in AI-linked markets look “punchy,” and more of the spending is being financed with debt; he discussed financial stability risks and gave no rate signal
- Germany Ifo Business Climate for October 2026: 90.2 (89.5 forecast; 89.9 previous)Above forecast
- U.K. CBI Distributive Trades for October 2026: -10.0 (-50.0 forecast; -55.0 previous)Above forecast
- U.S. Chicago Fed National Activity Index for September 2026: 0.07 (-0.1 forecast; -0.08 previous)Above forecast
- U.S. Dallas Fed Manufacturing Index for October 2026: 13.4 (7.0 forecast; 9.8 previous)Above forecast
Why it mattered: the raw materials prices index rose to 55.3, and the 10-year yield climbed off its day low near 4.96% after the 10:30 am ET release.
Broad Market Price Action: Oil Slides on Iran Diplomacy as AI Stocks Lift the S&P 500
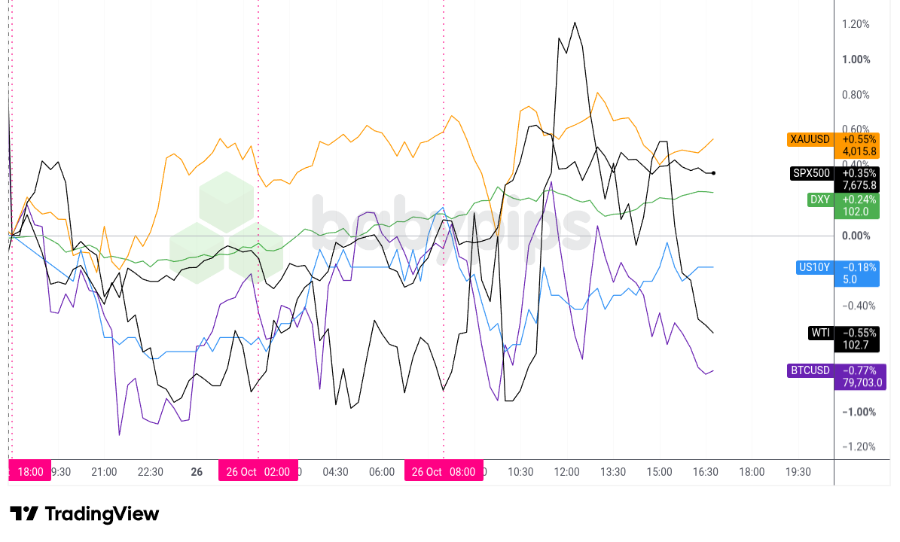
Two stories set the tone. The Iran talks in Tehran with Saudi, Pakistani and Turkish delegations pulled oil lower from the Asian open, after Brent closed Friday at its highest level since March. Then Anthropic filed its S-1 just after the 9:00 am ET mark, and chip and AI stocks rallied as the Philadelphia chip index rose about 3%. U.S. data stayed second tier, but the Dallas Fed survey at 10:30 am ET beat forecasts and showed input prices still climbing.
WTI crude oil opened the week about 0.7% below Friday’s close near $104.88 and slid through the Asian session to near $102.14 around 11:30 pm ET Sunday. A jump toward $103.40 around 9:00 am ET faded fast, and crude hit its day low near $101.78 around 10:30 am ET while the Tehran meetings ran. The drop reversed within the hour. WTI climbed to near $104.61 by 12:30 pm ET, and further Houthi attacks on Saudi Arabia likely kept supply worries in play. Oil ended near $103.05, down about 1.7%.
The 10-year Treasury yield rose through London to near 5.01% around 8:00 am ET, then dropped to its day low near 4.96% around 10:15 am ET as oil sank. Cheaper crude probably eased some inflation worry ahead of Wednesday’s Federal Reserve decision, where a hold is widely expected. The yield bounced to near 4.99% after the Dallas Fed survey and finished about 1 basis point lower on the day.
The S&P 500 opened near 7,640 and rallied to a day high near 7,702 by 11:00 am ET as AI names rebounded from last week’s selloff. Meta’s plan to raise up to $95 billion in equity for AI infrastructure added to the theme. The index gave back part of the gain around midday and closed near 7,676, up about 0.7%, with Microsoft, Alphabet and Amazon still due to report later in the week.
Gold dipped to near $3,978 around 9:00 pm ET Sunday, just above Friday’s three-month low, then climbed back above $4,000 during the Asian session. A firmer dollar knocked it to near $3,989 around 9:45 am ET. Gold then rallied about $30 in the next hour as oil and yields fell together, peaking near $4,030 around 1:00 pm ET. Softer oil likely tempered inflation concerns, and gold ended near $4,013, up about 0.4%.
Bitcoin started Sunday evening near $80,155, already below its Friday afternoon level near $81,300, and hit a low near $79,255 around 11:45 pm ET. It slipped back to near $79,300 at the U.S. stock open, then bounced to near $80,710 by 11:15 am ET as tech shares rallied. No crypto-specific catalyst stood out. Bitcoin faded with stocks after midday and finished near $79,870, down about 0.4%, which fits a day when risk appetite stayed concentrated in AI stocks.
Forex concept of the dayWhy can falling oil prices pull Treasury yields lower and lift gold?
Oil feeds straight into fuel and shipping costs, so a drop in crude can trim inflation expectations and bets on further Fed hikes, and bond yields tend to follow those bets lower. Gold pays no interest, so lower yields cut the cost of holding it. On Monday, WTI’s slide toward $101.78 came as the 10-year yield hit its low near 4.96%, and gold gained about $30 over the following hour. Learn the yield side of that chain in How Bond Yields Affect Currency Movements.
FX Market Behavior: U.S. Dollar vs. Majors
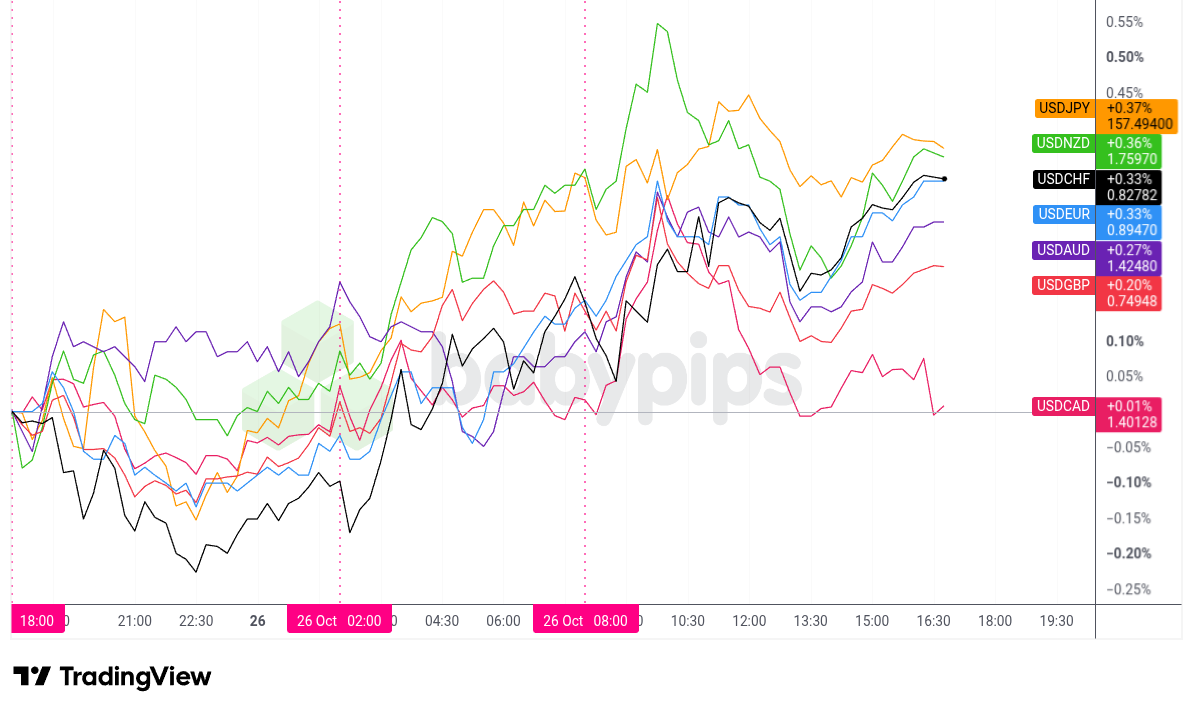
The dollar rose against all seven majors, and the U.S. Dollar Index gained about 0.2% to near 102.0. The yen was the weakest major, down about 0.4%, with the franc and the kiwi close behind near 0.3%. The Aussie, euro and pound each slipped about 0.2%, and the Canadian dollar held up best with a loss of about 0.1%. The London session did most of the work.
The Asian session opened with small weekend gaps. The euro opened firmer after Moody’s held France’s credit rating steady late Friday, while the yen and the Canadian dollar opened softer. The dollar then eased, and the Dollar Index touched its day low near 101.58 around 10:30 pm ET as USD/JPY dipped to near 156.65, with no clear catalyst. Reserve Bank of Australia Assistant Governor Brad Jones spoke on financial stability risks and offered no rate signal, and the Aussie drifted lower with the kiwi.
The dollar climbed steadily through the London session, likely helped as the 10-year yield rose back toward 5.0%. USD/JPY, USD/CHF and USD/NZD gained about 0.3% each between 3:00 am and 8:00 am ET, and the Dollar Index reached near 101.90. The euro got little lift from a firmer Ifo survey, as elevated energy prices probably still weighed on the euro zone outlook. The pound slipped even though the CBI survey showed U.K. retail sales falling at the slowest pace in 18 months.
The dollar peaked early in the U.S. session, with the Dollar Index near 102.06 around 9:45 am ET, then eased as Treasury yields fell. USD/CAD jumped to near 1.4055 around 10:15 am ET as oil sank toward its low, then dropped back to near 1.4002 by 1:30 pm ET as crude rebounded. USD/JPY still pushed to a day high near 157.64 around 11:30 am ET, and the dollar firmed again against most majors into the close.
On Premium this weekUSD/CAD swung with oil on Monday, and Wednesday brings both the Bank of Canada and the Fed. This week’s Fundies Cheat Sheet notes that futures put the chance of a Fed hold near 90%, so Fed Chair Kevin Warsh’s press conference may matter more than the decision itself. It’s part of Babypips Premium.
Upcoming Potential Catalysts: U.S. Durable Goods, Australia CPI and RBNZ Decision
- U.S. Durable Goods Orders for September 2026 at 12:30 pm GMT Tuesday: the Census Bureau report is the first top-tier U.S. release of Fed week, with a 1.5% m/m rise expected after a flat August, and it offers a read on business investment.
- Australia CPI for September 2026 at 12:30 am GMT Wednesday: the ABS monthly inflation data is seen at 4.2% y/y after 4.0%, and a firm print may add to bets on another Reserve Bank of Australia hike on Nov. 3.
- RBNZ Interest Rate Decision at 1:00 am GMT Wednesday (press conference at 2:00 am GMT): the Reserve Bank of New Zealand is expected to raise its cash rate to 3.00% from 2.75%, so the kiwi may react to how far it signals more hikes.
Also on the calendar (GMT):
- China Communist Party Fifth Plenum from 12:00 am GMT Tuesday
- U.S. Building Permits Final for September 2026 at 12:00 pm GMT
- U.S. ADP Employment Change Weekly for October 10, 2026 at 12:15 pm GMT
- U.S. S&P/Case-Shiller Home Price Index for August 2026 at 1:00 pm GMT
- U.S. CB Consumer Confidence for October 2026 at 2:00 pm GMT
- U.S. New Home Sales for September 2026 at 2:00 pm GMT
- U.S. Atlanta Fed GDPNow for Q3 2026 at 3:00 pm GMT
- Euro area ECB President Lagarde Speech at 5:00 pm GMT
- U.S. API Crude Oil Stock Change for the week ending October 23, 2026 at 8:30 pm GMT
- Australia RBA Senate Appearance at 12:15 am GMT Wednesday
Wednesday is the crowded day: the Bank of Canada decides at 1:45 pm GMT, the Fed follows at 6:00 pm GMT with a hold at 3.75% to 4.00% widely expected, and Microsoft and Alphabet report after the U.S. close. Until then, oil may keep trading on headlines from Tehran and Saudi Arabia, and the 10-year yield could decide whether gold holds above $4,000 and how much further the dollar runs.
Prefer email updates? The Babypips Daily Newsletter sends market news and trading tips to your inbox.
Stay frosty out there, forex friends!
AI disclosure: A Babypips editor researched and directed this article, and AI tools helped analyze the intraday price data, research sources, initiate the draft, before a Babypips editor did the final review and edit. AI tools can misread data, make arithmetic errors, and state wrong information in a confident tone. Prices, levels, and percentage moves here are approximate because the market data was not captured at the exact close, so check the figures against your own data source before you rely on them. The explanations for market moves are possible reasons, not confirmed causes. This article is for education and is not a recommendation to trade.
Related Articles
- Forex News
Financial & Forex Weekly Recap: October 19 – 23, 2026
- Stock Markets News
investingLive Americas FX news wrap 26 Oct: Anthropic IPO puts AI back in focus as stocks rebound
- Forex News
Fundies Cheat Sheet, Oct 26–30, 2026
- Stock Markets News
investingLive Americas FX news wrap 28 Oct: Fed holds rates, yield curve steepens as Big Tech earnings diverge
- Stock Markets News
investingLive Asia-Pacific market news: Oil eases on Vance’s Iran outreach