Financial & Forex Market Recap: Nov. 3, 2026


On Tuesday, Nov. 3, 2026, Iran draft-deal reports whipsawed oil, a JOLTS beat lifted yields and USD/JPY, and the Aussie slipped after the RBA’s split hike.
Iran headlines, a chip rebound and a strong U.S. jobs-openings report ran Tuesday’s markets. Reports of a U.S.-approved draft deal with Iran appeared to whipsaw WTI crude oil and briefly lift gold, while chipmakers helped the S&P 500 edge up about 0.3% as U.S. midterm voting got under way. A stronger-than-expected JOLTS report then pushed the 10-year Treasury yield to near 4.96%, and the dollar ended firmer against the yen and the Australian dollar.
In short: On Tuesday, Nov. 3, 2026, reports of a U.S.-approved draft deal with Iran appeared to whipsaw oil, and WTI crude oil ended near $97.66, up about 0.3%. A chip rebound lifted the S&P 500 about 0.3%, a JOLTS beat pushed the 10-year yield to about 4.96%, and gold slipped 0.7%. The Australian dollar lagged after the RBA’s split-vote hike.
Tuesday’s Market Scoreboard: Oil Whipsaw, Chip Rebound and a Firmer Dollar
| Asset | Close (approx.) | Day change | Driver |
|---|---|---|---|
| S&P 500 | 7,565 | +0.3% | Chip rebound, Iran deal reports |
| U.S. 10-year yield | 4.96% | +1.0% (about +5 bp) | JOLTS beat lifted yields |
| U.S. Dollar Index | 101.9 | +0.1% | JOLTS beat, higher yields |
| WTI crude oil | $97.66 | +0.3% | Iran draft-deal whipsaw |
| Gold | $3,921 | -0.7% | Higher yields, firmer dollar |
| Bitcoin | $77,780 | +1.5% | Tracked tech rebound |
| USD/JPY | 158.72 | +0.5% | Higher U.S. yields after JOLTS |
| EUR/USD | 1.1193 | 0.0% | Round trip on U.S. data |
| GBP/USD | 1.3413 | +0.1% | Steady before Thursday’s BoE |
| USD/CHF | 0.8210 | +0.3% | Swiss CPI pop faded |
| AUD/USD | 0.6966 | -0.5% | Split-vote RBA hike |
| NZD/USD | 0.5610 | -0.1% | China yuan curbs |
| USD/CAD | 1.4003 | +0.1% | Firmer dollar after JOLTS |
Approximate levels, 6:00 pm ET Monday to 4:00 pm ET Tuesday. Drivers are likely factors, not confirmed causes.
Forex News Headlines & Data: RBA Hike, Swiss CPI, U.S. JOLTS and Iran Draft-Deal Reports
- The U.S. carried out strikes on Iran’s Qeshm Island late Monday U.S. time; a U.S. official said they targeted surface-to-air missiles used against U.S. assets, and another said they appeared limited
- China’s central bank said it will raise its foreign exchange reserve requirement ratio to 6% from 4% from Nov. 15, and it set the USD/CNY reference rate at 6.7150, 661 pips weaker than a Reuters estimate of 6.6489
-
Australia RBA Cash Rate Decision for November 2026: 4.85% (4.85% forecast; 4.60% previous)In line
Why it mattered: six Board members voted for the hike and three voted to hold, and the Board only said it will stay “attentive to the data.” Traders likely read the three dissents as a sign the RBA may be close to done, and AUD/USD slipped about 15 pips in the 15 minutes after the 10:30 pm ET Monday release. - Switzerland CPI for October 2026: 0.2% m/m (0.0% m/m forecast; 0.0% m/m previous); 1.5% y/y (1.3% y/y forecast; 1.0% y/y previous)Above forecast
- Qatar’s Foreign Ministry said the U.S. and Iran remain committed to mediation efforts and are reviewing proposals aimed at bridging their differences
- Qatari newspaper Al-Araby Al-Jadeed reported, citing sources close to the mediators, that Washington had approved a draft memorandum of understanding presented to Iran on Monday; senior Iranian security official Mohsen Rezaei later called the U.S. response “not convincing”
- U.S. JOLTS Job Openings for September 2026: 7.523 million (7.06 million forecast; 7.19 million previous)Above forecast
Why it mattered: openings reached their highest level since May and quits rose to 3.4 million. A firmer job market may keep the Fed leaning toward tighter policy, and the 10-year yield rose about 3 basis points within 20 minutes of the 10:00 am ET release. - U.S. Factory Orders for September 2026: 1.8% m/m (1.2% m/m forecast; 0.3% m/m previous)Above forecast
- Americans voted in the U.S. midterm elections, with polls and nonpartisan analysts favoring Democrats to win the House while control of the Senate remains uncertain
Broad Market Price Action: Iran Draft-Deal Reports Whipsaw Oil as Chips Lift Stocks
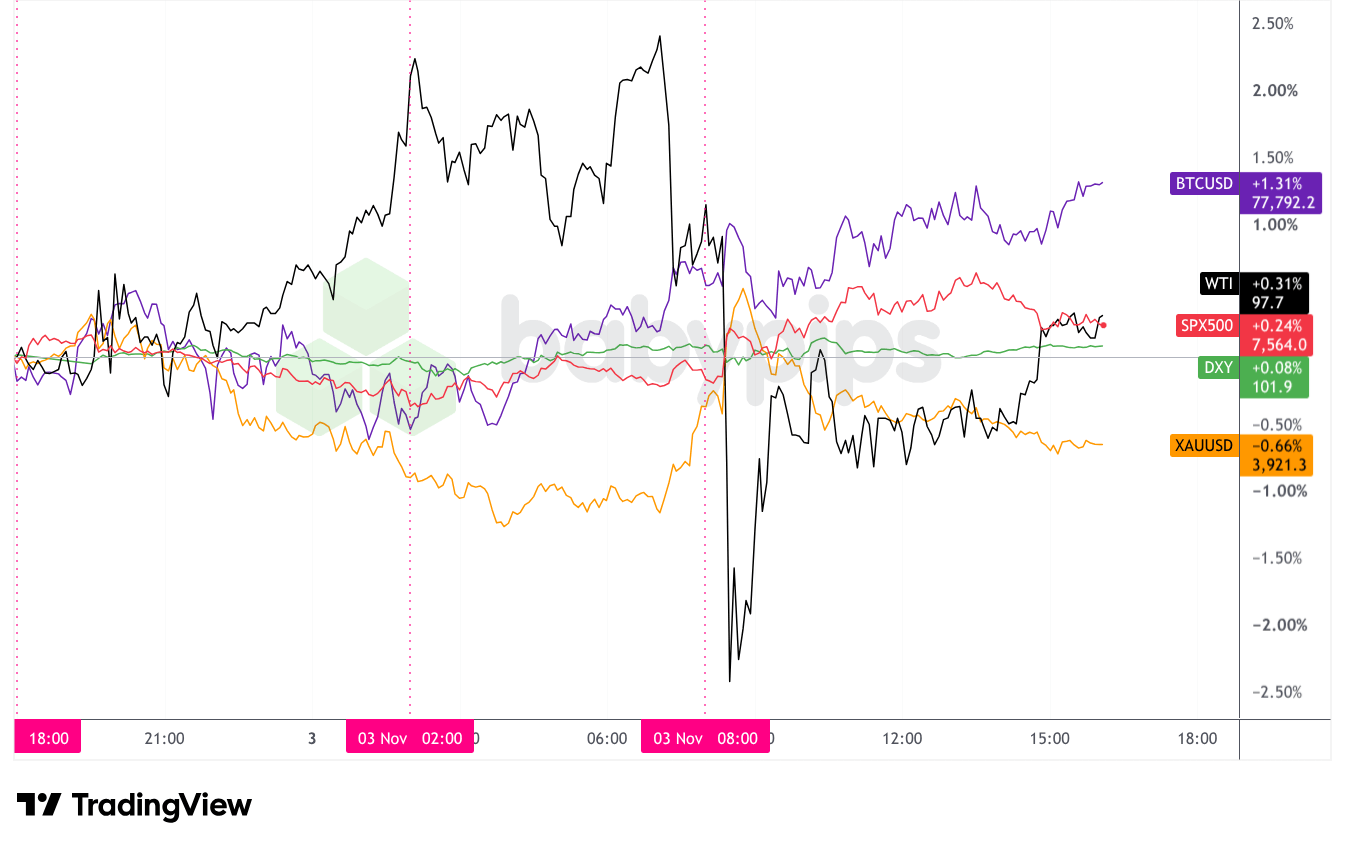
Iran headlines likely drove most of Tuesday’s swings in oil and gold. The U.S. strikes on Qeshm Island late Monday, plus a senior Iranian official’s comment that the two sides were still far from a deal, probably kept a war-risk premium in crude through the Asian session. Then around 8:28 am ET, wires picked up the Al-Araby Al-Jadeed report that Washington had approved a draft memorandum of understanding. WTI dropped more than $3 within minutes, gold jumped about $24, stocks rose and the 10-year yield dipped, which looks like traders pricing out some war risk. Less risk of a supply shock means cheaper oil, and cheaper oil eases the inflation worries that tend to push bond yields higher.
The relief didn’t last. Iranian officials pushed back later in the morning, and senior security official Mohsen Rezaei called the U.S. response “not convincing”. Oil likely recovered on that pushback and finished near $97.66, up about 0.3%. Traders may keep some war premium in crude until Tehran signs off on a deal.
Stocks leaned on chips. The S&P 500 rose about 0.3% on the chart, and the cash index closed up 0.36% at 7,568.92, as chipmakers bounced back from last week’s losses ahead of AMD’s results after the close. Nvidia rose 2.3% and Micron 2.6%, while Apple fell 1.9% after warning that memory-chip costs will keep rising. Afternoon gains faded after the Reuters report on SK Hynix’s held-up equipment approvals, which may have weighed on chip stocks. Bitcoin rose about 1.5% to near $77,780 with no crypto-specific catalyst, so it probably tracked the tech rebound.
The bigger story for rates came at 10:00 am ET, when JOLTS showed job openings at 7.52 million, well above forecasts. Strong hiring demand may have nudged traders toward pricing more Fed tightening, and the 10-year Treasury yield rose about 5 basis points on the day to near 4.96% (a basis point is 0.01 percentage point). Higher Treasury yields and a firmer dollar likely took the shine off gold, which pays no interest, and the metal gave back its draft-deal bounce to finish down about 0.7% near $3,921.
Forex concept of the dayWhy can a rate hike weaken a currency?
Traders price in a central bank decision before it happens, so a widely expected hike often does little for the currency on the day. The surprise sits in the details, such as the vote split or hints about what comes next. On Tuesday, the RBA hiked to 4.85% as forecast, but three of nine Board members voted to hold, and the Aussie fell about 0.5% to finish as the second-weakest major. Learn how to read those expectations in What Has the Market Already Priced In?.
FX Market Behavior: U.S. Dollar vs. Majors
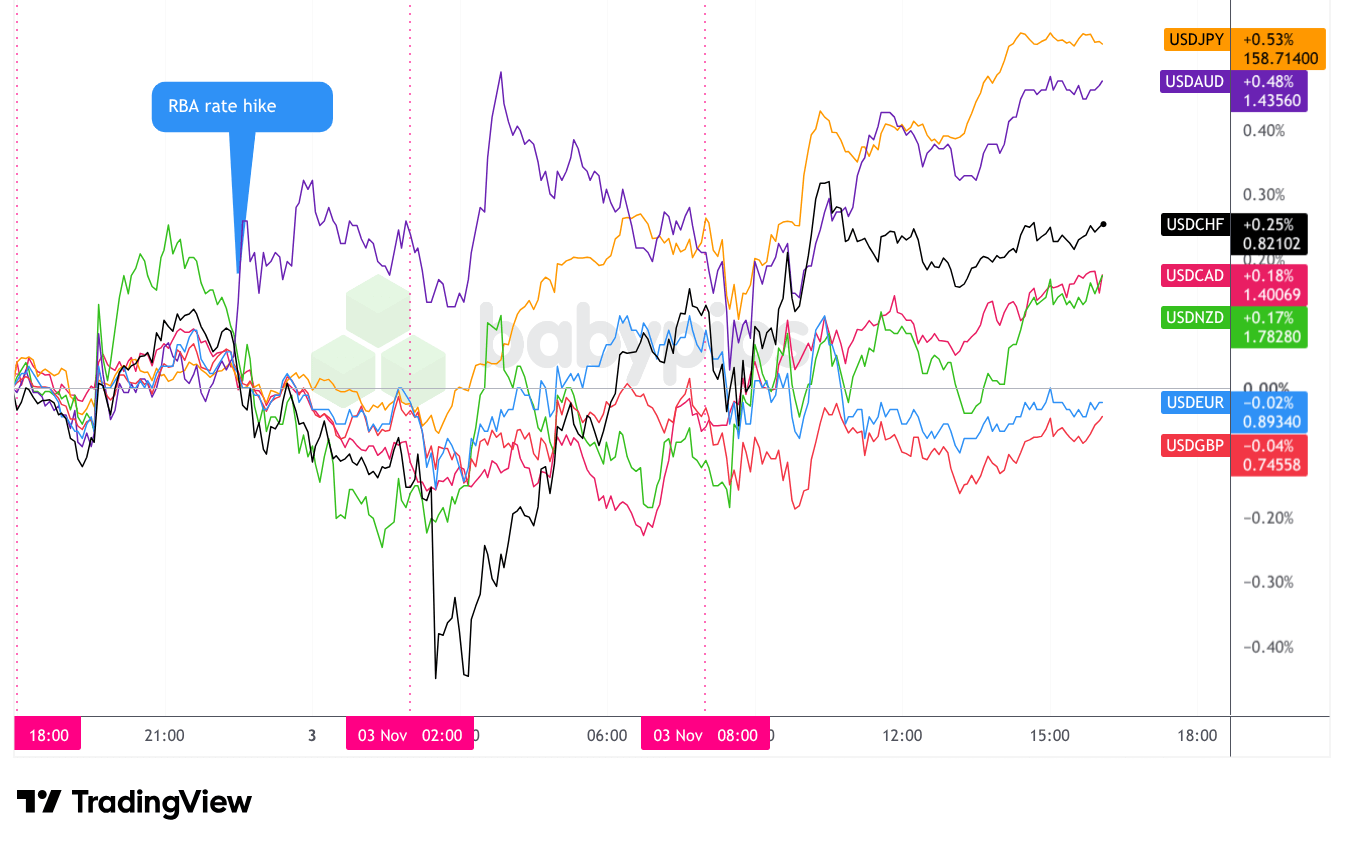
The yen and the Australian dollar finished at the bottom of the majors, each down about 0.5% against the dollar, while the pound edged up about 0.1% and the euro ended about flat. The franc slipped about 0.3%, and the kiwi and the Canadian dollar each lost about 0.1%. The U.S. Dollar Index ended near 101.86, up about 0.1%.
U.S. yields likely did the heavy lifting for USD/JPY, which rose about 0.5% to near 158.72. The JOLTS beat pushed Treasury yields higher, and a wider U.S.-Japan yield gap tends to favor the dollar over the yen. Japanese markets were closed for a holiday, which may have left the yen with thinner support. The Iran draft-deal report appeared to knock the dollar lower for a short while, but the JOLTS release flipped that move, and the broader dollar bid probably kept the Canadian dollar slightly lower even with oil up on the day.
The Australian dollar’s slide probably came from the details of the RBA decision rather than the hike itself. The RBA raised its cash rate to 4.85% as expected, but three of nine Board members voted to hold, and the statement gave no hint of more hikes. Traders may have read that as the tightening cycle nearing its end. China likely added to the pressure on the Aussie and the kiwi. The People’s Bank of China said it will raise its FX reserve requirement ratio and set a weaker-than-expected yuan fix, steps traders likely read as an effort to slow the yuan’s rally. The New Zealand dollar often trades as a proxy for China’s economy, which may explain its early dip.
The Swiss franc got a short lift from inflation that it couldn’t keep. Swiss headline CPI rose to 1.5% y/y, above the 1.3% forecast, and the franc jumped right after the 2:30 am ET release. The gains faded, probably because core inflation held at 0.5% and an energy-driven bump in the headline rate may not change the SNB’s thinking much. The franc then lost more ground as U.S. yields rose after JOLTS, and USD/CHF finished up about 0.3%.
On Premium this weekThe RBA hiked as expected on Tuesday, yet the Aussie still finished as the second-weakest major. Our Event Guide: RBA Monetary Policy Statement (November 2026) previewed the decision and how AUD might react, and this week’s Fundies Cheat Sheet: Nov. 2 to 6, 2026 covers the oil, AI earnings and jobs stories still in play. Both are part of Babypips Premium.
Upcoming Potential Catalysts: Euro Area CPI, BoE Decision and U.S. Jobs Report
- Euro Area Inflation Rate Flash for October 2026 at 10:00 am GMT Wednesday: forecasts range from 3.8% y/y on the BabyPips calendar to 4.0% elsewhere, against 3.8% previous, and a hot print may test the ECB’s October pause.
- Bank of England Interest Rate Decision at 12:00 pm GMT Thursday: forecasts call for a hike to 4.00% from 3.75%, so the MPC vote split and Governor Andrew Bailey’s press conference at 12:30 pm GMT may matter more for the pound than the decision itself.
- U.S. Non-Farm Payrolls for October 2026 at 1:30 pm GMT Friday: the BabyPips calendar shows a 40K forecast against 29K previous, with the unemployment rate seen at 4.2%. After Tuesday’s JOLTS beat, a strong print may add to bets on another Fed hike.
Also on the calendar (GMT):
- New Zealand Unemployment Rate for Q3 2026 at 9:45 pm GMT Tuesday (5.5% forecast; 5.6% previous)
- AMD earnings after the U.S. close Tuesday, then U.S. midterm results through the Asian session
- U.S. ADP Employment Change for October 2026 at 1:15 pm GMT Wednesday (80K forecast; 90K previous)
- U.S. Treasury Quarterly Refunding Announcement at 1:30 pm GMT Wednesday
- U.S. ISM Services PMI for October 2026 at 3:00 pm GMT Wednesday (54.5 forecast; 54.9 previous)
- Australia Balance of Trade for September 2026 at 12:30 am GMT Thursday
- U.S. Initial Jobless Claims at 1:30 pm GMT Thursday (195K forecast; 194K previous)
- Canada Employment Change for October 2026 at 1:30 pm GMT Friday (14.0K forecast; -68.3K previous)
- U.S. UoM Consumer Sentiment Prel for November 2026 at 3:00 pm GMT Friday (47.0 forecast; 48.0 previous)
Iranian officials say no deal is final, and the first midterm results arrive after polls start closing at 6:00 pm ET, so oil and the dollar may stay jumpy heading into Thursday’s BoE decision and Friday’s jobs report.
Prefer email updates? The Babypips Daily Newsletter sends market news and trading best practices to your inbox.
Stay frosty out there, forex friends!
Disclaimer: This article is for educational purposes only. It isn’t investment or trading advice or a recommendation to trade. Prices, levels, and percentage moves here are approximate because the market data was not captured at the exact close. The explanations for market moves are possible reasons, not confirmed causes.
AI disclosure: The Babypips editorial team used AI tools to help research, write, and check this article. A Babypips editor reviewed and edited it before publication. AI tools can misread data, make arithmetic errors, and state wrong information in a confident tone. Check figures and quotes against the linked sources before you rely on them. Our Editorial Policy explains how we create and review our content.