Why retirement planning needs a health check


For advisors, the spectre of ailments for clients – and the financial consequences – should be on the radar

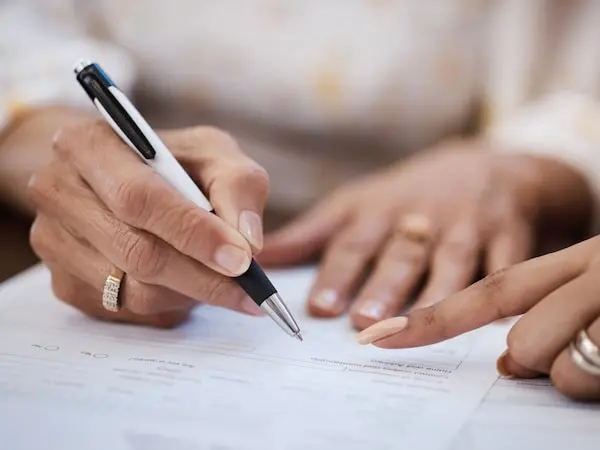
Advisors can help clients plan the assets needed to fund retirement, and focus on the health to enjoy it.GETTY IMAGES
“The first wealth is health,” poet and philosopher Ralph Waldo Emerson once wrote. In financial planning, health typically takes a backseat to dollars and cents, even though it’s also central to achieving life goals.
Retirement plans often project income needs to age 95, says Julie Seberras, head of wealth planning at Manulife Wealth in Toronto. That’s prudent at a time when Canadians are living longer, but, she says, “a lot of that [planning] is tied to being healthy so that your clients will live their best lives in retirement.”
That’s not always the case. Statistics Canada reports that more than seven in 10 Canadians aged 65 and older will have at least one of 10 chronic conditions, including hypertension, osteoarthritis, heart disease and diabetes. Other Statistics Canada findings show that about one-quarter of Canadians are forced to retire early because of their or their spouse’s poor health.
For advisors, the spectre of ailments for clients – and the financial consequences – should be on the radar. It’s a major risk to manage, says Karen Henderson, an independent planning specialist and founder of the Long Term Care Planning Network in Toronto.
“I have been educating advisors about this for years,” she says, adding that the industry remains focused on its core offering: making money for clients.
Although that’s understandable, she says best-in-class advisors take additional time to talk about physical and cognitive health and its impact on either the capacity to earn money to meet financial goals, or on finances once clients are retired.
“It astounds me that many advisors don’t recognize the added value,” Ms. Henderson says.
Many advisors do have risk management discussions about disability and critical health insurance. But Ms. Henderson says they should “overstep” the norms of such conversations to reinforce the importance of physical fitness and eating well in achieving financial goals.
“That has an impact on daily routines, retirement and finances,” says Dr. Olga Theou, a Canada Research Chair in physical activity, mobility and health aging, and an associate professor at Dalhousie University in Halifax. “Simply, your current health state is one of your best predictors of your future health.”
She says we’ll all likely spend a significant part of our lives with various levels of frailty, with reduced physical strength and ability, making us prone to other diseases and injuries. That’s just aging, and given the potential impact of health-related decline on just about every Canadian, Ms. Seberras says advisors should go beyond the financial “Plan A” about the desired outcomes for clients.
“That’s the aspirational one,” she says. “But advisors must also have conversations about what if Plan A doesn’t work.”
Risk management could include discussions about insurance, power of attorney, a health directive and a will. Beyond that, advisors could dig more deeply into their clients’ health and fitness to emphasize the connection with financial wellness, Ms. Seberras adds.
“It’s really important that advisors have tough conversations about what the plan looks like if their mobility, for example, is negatively affected.”
Wealth that was previously dedicated for lifestyle and legacy can often go toward out-of-pocket health care costs instead. A 2025 report from Scotia Wealth Management says the average cost of in-home care is $37 an hour, with the Canadian Medical Association noting “moderate care” involves 22 hours per week, translating into more than $3,000 a month. Meanwhile, long-term care costs can range from $2,000 to $6,000 a month.
These costs should be considered in clients’ “Plan B”, Ms. Seberras says, which has another benefit of encouraging them indirectly to take preventative measures today.
“It’s showing them the financial realities of what an unhealthy lifestyle and health event look like and the impact on what they want to achieve.”
Related Articles
- Stock Markets News
Who will care for you in retirement? New survey of Canadians finds common blind spot
- Stock Markets News
How to plan for retirement when your goals don’t match your spouse’s
- Stock Markets News
Why Gwen, 54, shouldn’t feel bad about spending a bit more in retirement
- Stock Markets News
This advisor wishes she had joined an advice-only firm earlier in her career
- Stock Markets News
OAS benefits represent shrinking share of retirees’ income, report finds