The US markets plunged sharply. Banxico unexpectedly cut interest rates


By JustMarkets
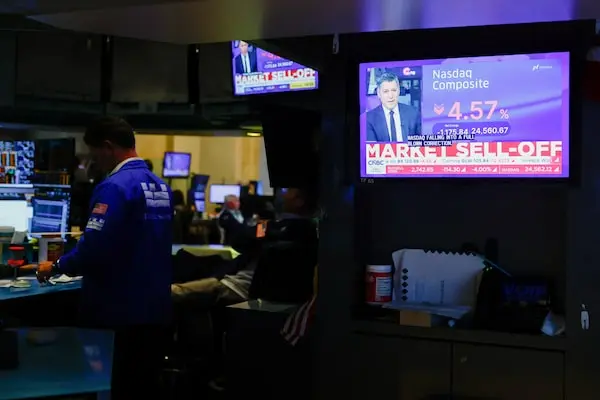
The selloff in US equities on Thursday marked the largest single-day market decline since the tariff shock of spring 2025. The sharp rebound on Wall Street on Wednesday reflected a classic relief rally following the removal of a key source of political uncertainty. By the close, the Dow Jones (US30) had fallen 3.43%. The S&P 500 (US500) lost 4.11%, while the technology-heavy NASDAQ (US100) posted a steep decline of 6.36%.
The primary catalyst behind the repricing was a fundamental shift in the AI sector and data center infrastructure industry. The Democratic Party’s victory in both chambers of Congress, combined with political changes at the state level, including gubernatorial races in key states such as Texas, has brought into focus the risks of moratoriums, stricter environmental standards for energy consumption, and antitrust investigations targeting hyperscale data centers. The semiconductor sector has become the epicenter of the selloff amid concerns over a slowdown in hyperscaler capital expenditures (CapEx). Dependence on cyclical memory demand and elevated chip pricing has triggered a reassessment of valuation multiples. Micron (-15%) and AMD (-15%) recorded the steepest declines amid heavy liquidation in the HBM memory and server GPU segments. Broadcom (-9%) and Nvidia (-8.5%) saw significant pullbacks across lithography-related equipment and specialized AI accelerators. Tesla (-11%) dropped on the back of broad-based selling in high-valuation technology stocks and a reassessment of regulatory risks facing autonomous transportation. Microsoft (-4%), Meta (-4%), and Oracle (-6.5%) declined less than the broader market as investors differentiated between the resilient balance sheets of major technology firms and the heightened risks facing hardware suppliers.
Banxico’s unexpected decision to cut its benchmark interest rate by 25 basis points to 6.25%, down from 6.50% and against market expectations, triggered a noticeable depreciation of the Mexican peso toward 18.80 per US dollar. The move highlights the central bank’s priority of supporting domestic economic growth amid ongoing disinflation, despite the risk of currency weakness. With Banxico easing policy while the Federal Reserve is still expected to maintain or potentially tighten its stance further, the interest rate differential between the US dollar and the peso has narrowed. For global investors, this compression in yield reduces the attractiveness of MXN carry trades, encouraging the unwinding of long peso positions.
The synchronized drop in Bitcoin (BTC/USD) to $76,000 alongside a broad cross-sector equity selloff underscores the profound restructuring underway across global financial markets. The collapse of the US technology sector, led by chipmakers, erased the post-election relief rally as Democratic control of Congress raised the prospect of restrictions on the expansion of energy-intensive data centers and tighter AI regulation. As a result, institutional investors are liquidating higher-risk assets to cover losses, redirecting liquidity into sovereign debt markets and compressing yield spreads.
In Europe, Germany’s DAX (DE40) declined 0.43%, France’s CAC 40 (FR40) closed 0.34% higher, Spain’s IBEX 35 (ES35) gained 0.59%, while the UK’s FTSE 100 (UK100) finished the session down 0.43%.
Norges Bank’s decision to keep rates unchanged at 4.50% following its 25-basis-point hike in September reinforces its higher-for-longer strategy. Against a backdrop of accelerating producer prices in the Eurozone and the Bank of England’s hawkish move to raise rates to 4.0%, Norway’s central bank is deliberately maintaining restrictive borrowing conditions to prevent inflation expectations from becoming entrenched amid supply disruptions and geopolitical tensions in the Middle East. For the Norwegian krone (NOK), the combination of a firm signal regarding the possibility of further tightening and the stabilization of oil prices around $90.50 per barrel serves as a strong supportive factor.
The rebound in crude oil prices (WTI) on Thursday to $90.50 per barrel, up 3%, illustrates the rapid return of a geopolitical risk premium following a steep three-day decline. While the outcome of the US midterm elections has increased the White House’s incentives to seek a swift resolution to the conflict through Qatari mediation, details emerging from diplomatic discussions reveal significant disagreement over the terms of any potential deal. Five maritime incidents and attacks on commercial vessels in the Persian Gulf since the beginning of the week confirm that, despite exports from GCC countries returning to near-normal levels, war-risk insurance premiums and freight rates remain at extremely elevated levels.
In Asia, Japan’s Nikkei 225 (JP225) fell 1.79%, China’s FTSE China A50 gained 1.83%, Hong Kong’s Hang Seng (HK50) surged 3.67%, and Australia’s ASX 200 (AU200) closed 2.61% higher.
The New Zealand dollar (NZD) weakened ahead of Saturday’s parliamentary elections due to the risk of a prolonged political deadlock. A near-even split between the center-right National Party and the center-left Labour Party, combined with the influence of smaller parties, increases the likelihood of weeks of difficult coalition negotiations. The absence of a clearly articulated fiscal strategy to address economic stagnation has left the currency without meaningful support. The NZD’s downside pressure has been amplified by the Reserve Bank of New Zealand’s (RBNZ) decision to unexpectedly pause its rate cycle, a development that has coincided with a rise in unemployment to 5.7%. In contrast to the aggressive hawkish stance of the Bank of England, with rates at 4.0%, and Norges Bank, with rates at 4.5%, the Reserve Bank of New Zealand has effectively acknowledged the end of its tightening cycle amid a weakening labor market.
S&P 500 (US500) 7,372.35 -316.27 (-4.11%)
Dow Jones (US30) 51,523.06 -1,833.06 (-3.44%)
DAX (DE40) 26,325.01 -112.66 (-0.43%)
FTSE 100 (UK100) 10,782.66 -46.55 (-0.43%)
USD Index 101.60 +0.03 (+0.03%)
News feed for: 2026.11.06
- Japan Average Cash Earnings (m/m) at 01:30 (GMT+2) – JPY (MED)
- German Industrial Production (m/m) at 09:00 (GMT+2) – EUR (LOW)
- Canada Unemployment Rate (m/m) at 15:30 (GMT+2) – CAD (HIGH)
- US Unemployment Rate (m/m) at 15:30 (GMT+2) – USD, XAU, US indices (HIGH)
- US Non-Farm Employment Change (m/m) at 15:30 (GMT+2) – USD, XAU, US indices (HIGH)
- US Michigan Consumer Sentiment (m/m) at 17:00 (GMT+2) – USD (MED)
- Canada Ivey PMI (m/m) at 17:00 (GMT+2) – CAD (MED)
By JustMarkets
This article reflects a personal opinion and should not be interpreted as an investment advice, and/or offer, and/or a persistent request for carrying out financial transactions, and/or a guarantee, and/or a forecast of future events.
Related Articles
- Stock Markets News
Markets plunge in a dramatic reversal from Wednesday’s stock market rally
- Economy News
Trading Day: A November 5 market bonfire
- Forex News
NASDAQ faces heavy selling pressure. Investors turn to Switzerland as a safe haven
- Forex News
Investors reduce positions ahead of the US midterm elections vote
- World News
Stocks tumble as midterms fuel AI fears and judge halts Trump’s D.C. arch: Morning Rundown