Financial & Forex Market Recap – Oct. 19, 2026


Treasury yields climbed and AI-linked stocks rebounded on Monday, lifting the dollar as French unrest weighed on the euro.
Bond yields ran the show on Monday. The 10-year Treasury yield climbed to near 5.15%, which helps explain why the yen finished as the weakest major, why gold slid and why Bitcoin stalled while the S&P 500 rose on a chipmaker rebound. Oil ended flat near $100 after a round trip.
In short: On Monday, Oct. 19, 2026, U.S. stocks rose about 0.5% as chipmakers rebounded, but the 10-year Treasury yield climbed to near 5.15%, which likely weighed on the rest of the board. The yen fell about 0.4% to finish as the weakest major, gold lost 0.6%, and Bitcoin gave back most of its early rally.
Monday’s Market Scoreboard: Yields, Yen, Gold and Stocks
| Asset | Close (approx.) | Day change | Driver |
|---|---|---|---|
| S&P 500 | 7,694 | +0.5% | Chipmaker rebound |
| U.S. 10-year yield | 5.14% | +1.3% (about +6 bp) | Oil, French bonds, tech rally |
| U.S. Dollar Index | 102.0 | +0.2% | Higher yields, early euro dip |
| WTI crude oil | $100.10 | -0.1% | Russia waiver vs. Houthi attacks |
| Gold | $4,140 | -0.6% | Higher yields, firmer dollar |
| Bitcoin | $81,850 | +0.3% | No clear catalyst, yields capped |
| USD/JPY | 158.54 | +0.4% | Wider U.S.-Japan yield gap |
| USD/CAD | 1.4108 | -0.15% | CPI spike faded |
| EUR/USD | 1.1213 | -0.1% | French riots, firmer dollar |
| GBP/USD | 1.3304 | -0.2% | Broad dollar bid |
| USD/CHF | 0.8268 | +0.2% | Broad dollar bid |
| AUD/USD | 0.6981 | +0.1% | Kent remarks, China GDP |
| NZD/USD | 0.5663 | 0.0% | No clear driver |
Approximate levels, 6:00 pm ET Sunday to 4:00 pm ET Monday. Drivers are likely factors, not confirmed causes.
Forex News Headlines & Data: China GDP, Canada CPI, BOJ and RBA
- France faced its worst street violence in years after weekend cost-of-living protests turned into riots, and the government announced partial curfews in Paris, Lille and Lyon
- BOJ Governor Kazuo Ueda: underlying inflation is “quite close” to the 2% target, with AI demand adding to price pressure; appropriate rate hikes would help avoid bond-yield spikes, ahead of the Oct. 30 meeting (markets expect a hold at 1.25%)
- RBA Assistant Governor Christopher Kent: “reasonable evidence” neutral rates are rising in Australia and globally; questioned whether the 4.60% cash rate is restrictive enough
- New Zealand Services PSI for September 2026: 50.9 (50.0 forecast; 51.2 previous)Above forecast
- New Zealand Balance of Trade for September 2026: -1.97B (-1.2B forecast; -1.35B previous)Below forecast
- China House Price Index for September 2026: -2.8% y/y (-3.1% y/y forecast; -3.0% y/y previous)Above forecast
- China GDP Growth Rate for Q3 2026: 4.5% y/y (4.6% y/y forecast; 4.3% y/y previous; a Reuters poll had 4.4%)Forecasts differ
Why it mattered: China is Australia’s biggest trading partner, and the Aussie held its gains after the release. - China Industrial Production for September 2026: 5.5% y/y (5.8% y/y forecast; 5.2% y/y previous)Below forecast
- China Unemployment Rate for September 2026: 5.2% (5.3% forecast; 5.3% previous)Below forecast
- China Retail Sales for September 2026: 1.1% y/y (1.0% y/y forecast; 0.4% y/y previous)Above forecast
- Canada CPI Growth Rate for September 2026: 3.1% y/y (3.2% y/y forecast; 3.0% y/y previous)Below forecast
Why it mattered: the Bank of Canada had flagged persistent inflation risks, so the softer print may have cooled hike bets and briefly knocked the loonie. - U.S. NAHB Housing Market Index for October 2026: 29.0 (31.0 forecast; 32.0 previous)Below forecast
Broad Market Price Action: Treasury Yields Climb as Stocks Bounce and Gold Slides
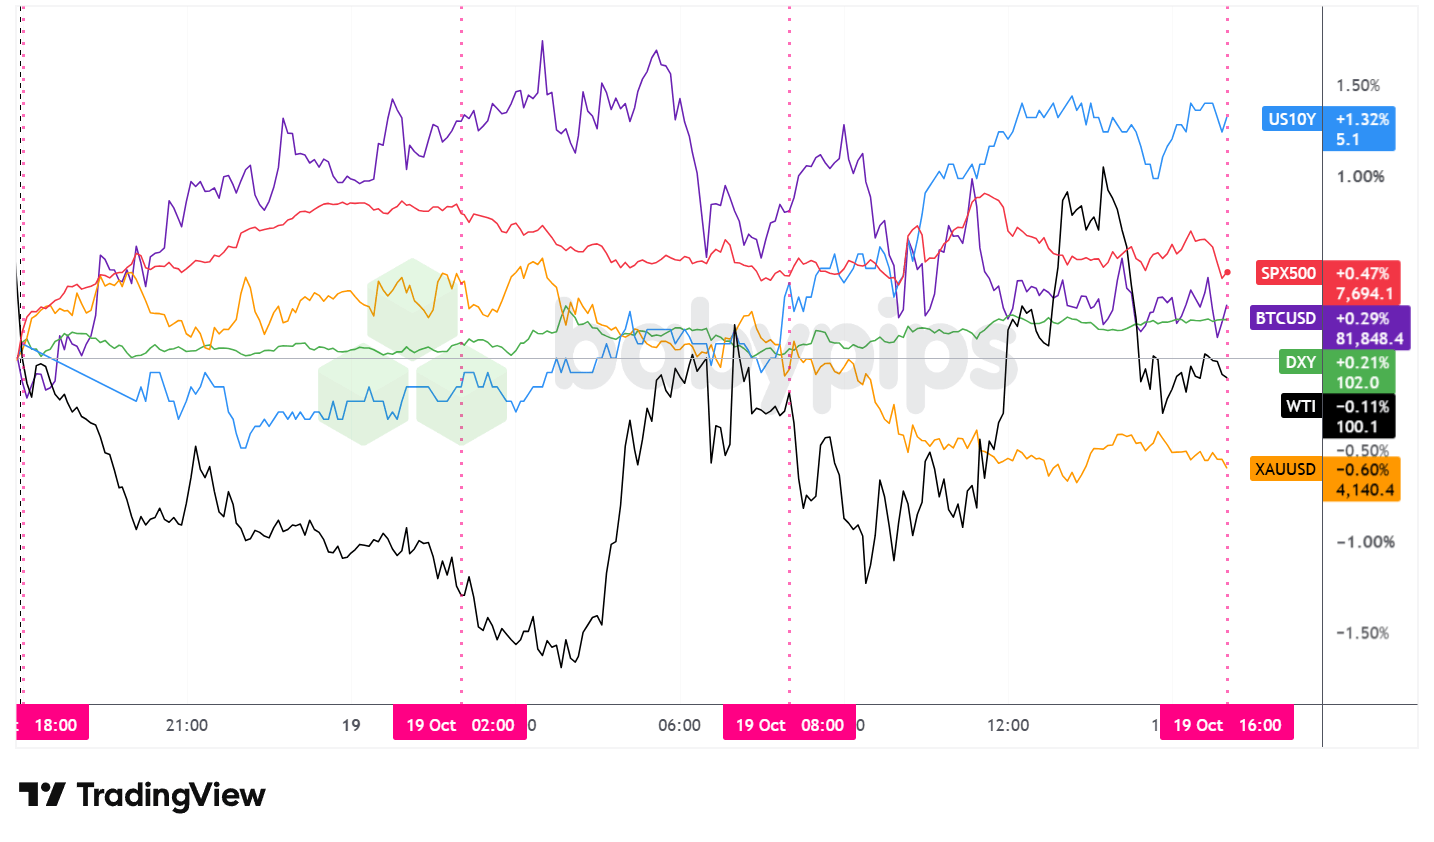
France’s weekend riots split the start of the week. European stocks and French bonds sold off and the euro opened lower, while U.S. stock futures climbed as chipmakers bounced from last week’s rout. A gauge of chip giants rose about 1.6% and the Nasdaq 100 added about 1.2%. Canada’s September CPI then came in at 3.1% y/y against a 3.2% forecast, and prices rose 0.1% m/m against a 0.3% consensus. Gasoline, up 27.8% from a year ago, drove the headline, while CPI excluding gasoline slowed to 2.2% from 2.4%. USD/CAD jumped at the 8:30 am ET release and gave back part of the move within the hour.
Premium members got the Canada CPI Event Guide on Friday, which framed the 3.2% consensus that Monday’s print undershot.
WTI crude oil slid in Asian trading to a low near $98.55 around 3:50 am ET. President Donald Trump signed an executive order on Friday that waived some sanctions and tariffs on Russian energy exports, and the prospect of more Russian fuel likely weighed on early prices. Crude climbed back above $100 in the London session and peaked near $101.30 around 1:45 pm ET as Yemen’s Houthis claimed new attacks on Saudi energy, airport and military targets. Those gains faded into the close, leaving oil near $100.10, down about 0.1%.
The 10-year Treasury yield dipped to near 5.05% early in the Asian session, then climbed through London and New York to a day high near 5.15% around 1:10 pm ET. Elevated oil prices and the hit to French bonds weighed on Treasuries, and the tech rebound probably drew some money out of bonds after last week’s flight to safety. October’s NAHB housing index fell to 29 against a 31 forecast, and the weak print did little to slow the climb.
The S&P 500 rose through Asian trading, dipped in London as European stocks fell, then hit a day high near 7,727 around 11:35 am ET with chipmakers in the lead. A report that Nscale was in talks to sell computing power to Anthropic in a deal worth about $45 billion likely helped AI names. The index gave back part of the rally into the close and ended near 7,694, with higher yields probably capping valuations ahead of Meta and Tesla earnings on Wednesday.
Gold peaked near $4,188 around 3:30 am ET, then slid through London and New York to a low near $4,137 around 1:15 pm ET. Rising yields and a firmer dollar likely weighed on the metal, which pays no interest. The stock rebound probably trimmed safe-haven demand, too.
Bitcoin rallied in Asia to near $83,000 around 3:30 am ET, then drifted lower for most of the day and finished near $81,850. No crypto-specific catalyst stood out, so higher yields and the firmer dollar likely capped prices even as stocks held gains.
Forex concept of the dayWhy do rising Treasury yields weigh on the yen and gold?
When U.S. yields climb while the Bank of Japan holds its rate near 1.25%, the gap between what dollars and yen pay widens, and money tends to drift toward the higher-yielding dollar. Gold pays no interest at all, so a higher Treasury yield raises the cost of holding it instead of a bond. Neither link holds every day, but both lined up on Monday as the 10-year rose about 6 basis points. Learn the mechanics in How Bond Yields Affect Currency Movements.
FX Market Behavior: U.S. Dollar vs. Majors
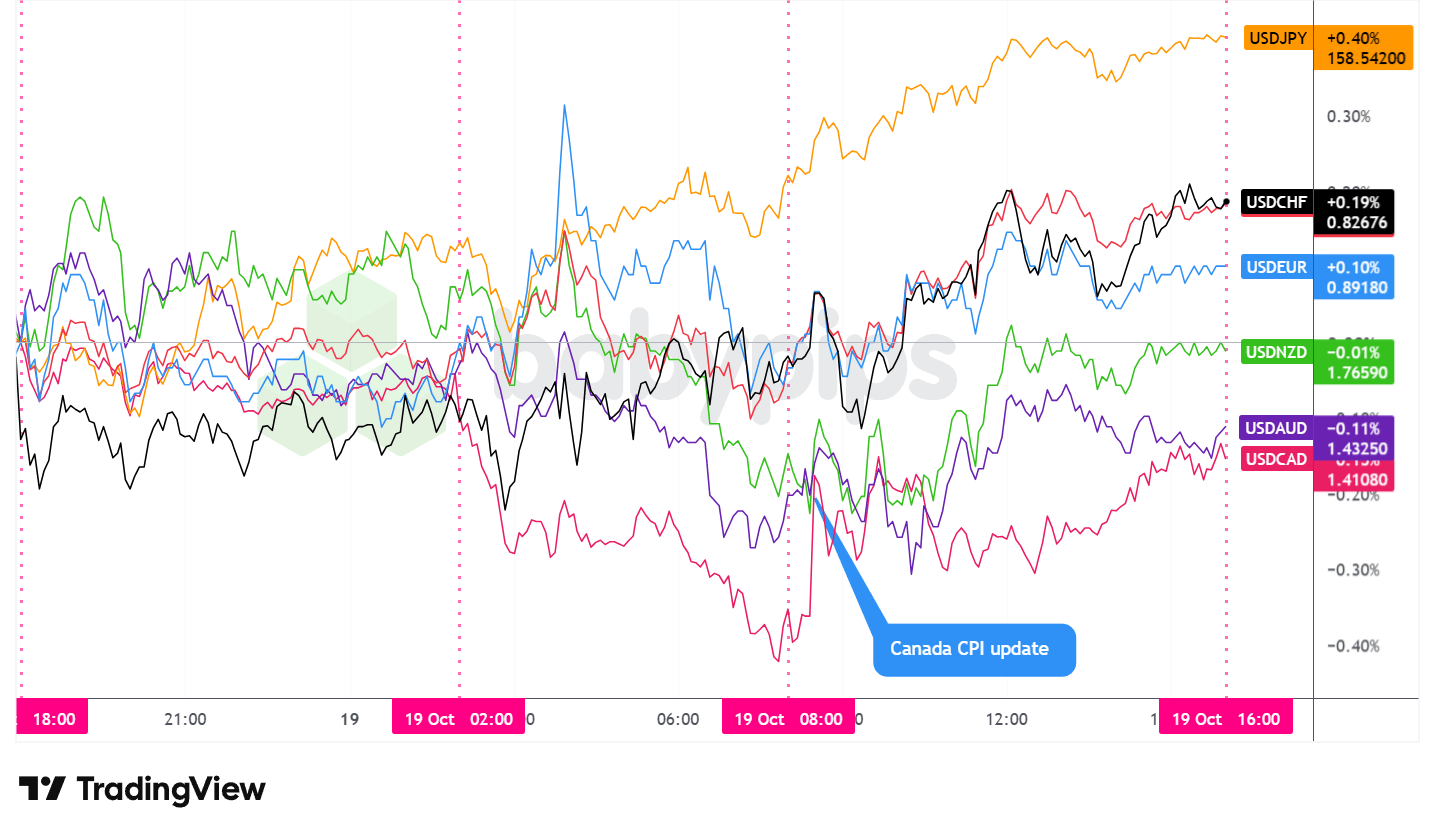
The yen finished at the bottom of the majors, down about 0.4% against the dollar, while the Canadian dollar topped the board with a gain of about 0.15%. The franc, pound and euro slipped, the Aussie edged up and the kiwi ended flat. The U.S. session did most of the work for the dollar as yields climbed.
The Asian session opened with a weekend gap. The euro opened about 0.2% below its last pre-weekend price as the French riots dominated headlines, then recovered part of that gap in the first few hours. The Australian and New Zealand dollars opened firmer, with no clear weekend driver. China’s Q3 GDP grew 4.5% y/y, up from 4.3% in Q2, and the Aussie held its gains after the release. RBA Assistant Governor Christopher Kent questioned whether policy is restrictive enough, which likely added support. The yen softened even after BOJ Governor Kazuo Ueda said underlying inflation is “quite close” to target, and the Canadian dollar firmed as oil slipped, against its usual link to crude.
The euro hit its weakest level of the day near 1.1190 around 4:00 am ET early in the London session as French bonds and stocks sold off, and that dip lifted the Dollar Index to a day high near 102.07. The euro’s climb back into the New York open looked like a partial unwind of the gap-driven selling. The Aussie and kiwi kept grinding higher through London, and the Canadian dollar reached its best level of the day, with USD/CAD near 1.4070 around 7:50 am ET.
The softer Canadian CPI hit the loonie at the start of the U.S. session, sending USD/CAD up about 0.2% to near 1.4105 within minutes. The pair gave back part of that jump, then crept higher into the close, likely helped by the broader dollar bid as yields rose. USD/JPY climbed to day highs near 158.55 late in the session, while the franc, euro and pound slipped as the dollar firmed through the U.S. morning. The Aussie gave back some of its earlier gains.
On Premium this weekUSD/JPY finished near 158.55, its high of the day, as the 10-year yield pushed toward 5.15%. This week’s Fundies Cheat Sheet flags the 10-year yield as the swing factor for how far the oil and AI-earnings stories reach the dollar and gold. It’s part of Babypips Premium.
Upcoming Potential Catalysts: U.K. Jobs, GDT Dairy Auction, Meta and Tesla Earnings
- U.K. Claimant Count Change and HMRC Payrolls Change for September 2026 at 6:00 am GMT Tuesday: the ONS labor market release is the pound’s first big data test of the week and may shift Bank of England rate expectations.
- New Zealand Global Dairy Trade Price Index at 12:00 pm GMT Tuesday: dairy is New Zealand’s largest export, so the GDT auction result can move the kiwi.
- Meta and Tesla earnings after the U.S. close on Wednesday (from 8:00 pm GMT):Meta and Tesla test the AI trade behind Monday’s chip rebound, and a big stock move may feed back into yields.
Also on the calendar (GMT):
- Australia RBA Connolly Speech at 10:50 pm GMT Monday
- Swiss Balance of Trade for September 2026 at 6:00 am GMT
- Germany PPI for September 2026 at 6:00 am GMT
- Germany ZEW Economic Sentiment Index for October 2026 at 9:00 am GMT
- ADP Employment Change Weekly for the four weeks ending October 3, 2026 at 12:15 pm GMT
- U.S. Building Permits Prel for September 2026 at 12:30 pm GMT
- U.S. Pending Home Sales for September 2026 at 2:00 pm GMT
- U.S. Atlanta Fed GDPNow
- BoE Greene Speech at 5:00 pm GMT
- API Crude Oil Stock Change for the week ending October 16, 2026 at 8:30 pm GMT
French protest organizers have called for another round of demonstrations next Saturday, so the euro may stay sensitive to headlines out of Paris. With oil still near $100 and the Fed in its pre-meeting quiet period, the 10-year yield could again decide how hard the yen and gold get pushed around.
Prefer free updates? The Babypips Daily Newsletter sends market news and trading tips to your inbox.
Stay frosty out there, forex friends!
AI disclosure: A Babypips editor researched and directed this article, and AI tools helped analyze the intraday price data, research sources, initiate the draft, before a Babypips editor did the final review and edit. AI tools can misread data, make arithmetic errors, and state wrong information in a confident tone. Prices, levels, and percentage moves here are approximate because the market data was not captured at the exact close, so check the figures against your own data source before you rely on them. The explanations for market moves are possible reasons, not confirmed causes. This article is for education and is not a recommendation to trade.